The VA Home Loan Benefit: One of the Most Valuable Perks You've Earned

Knowing how to apply for a VA home loan can save you tens of thousands of dollars — but the process trips up a lot of veterans who aren't sure where to start.
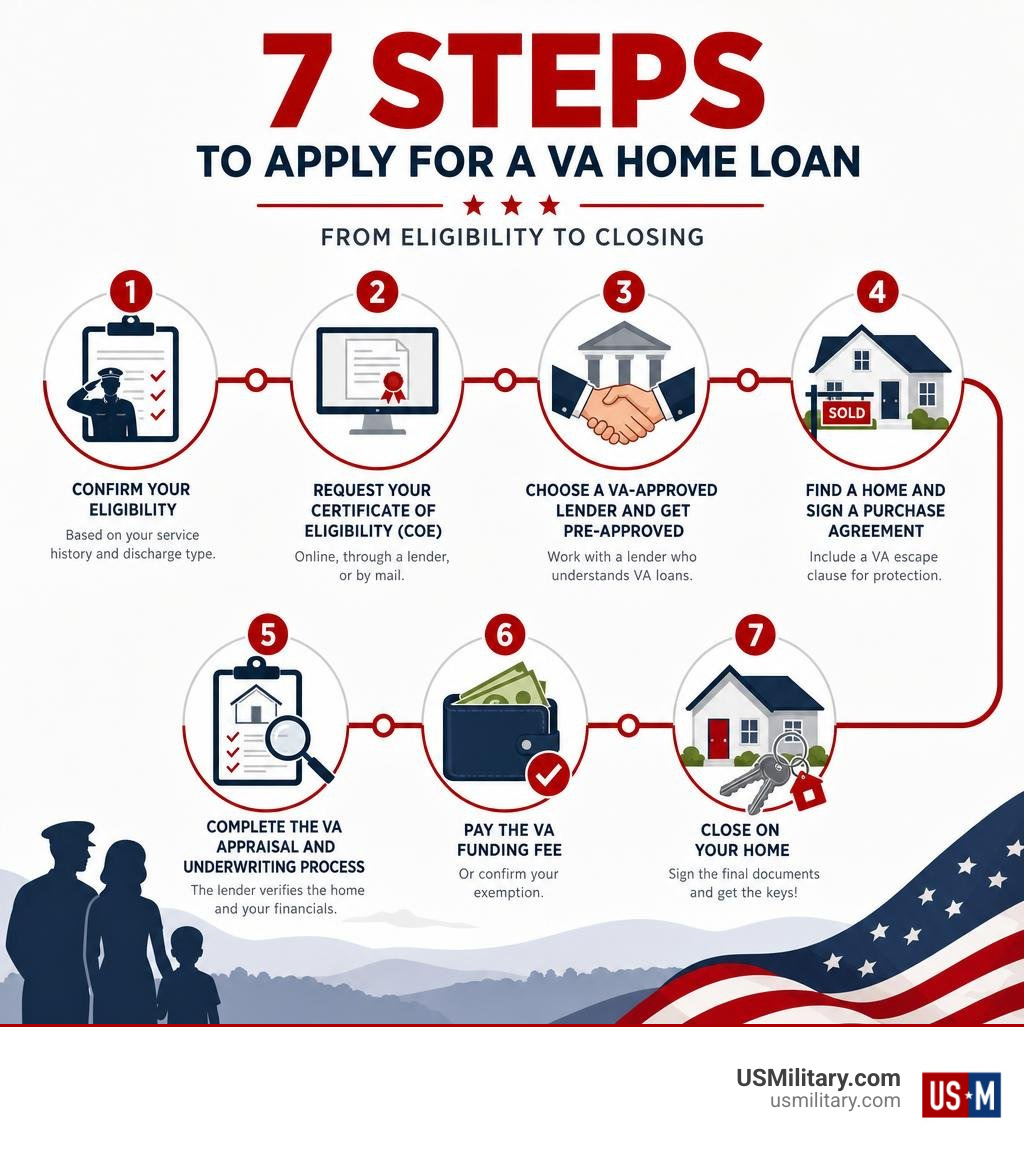
Here's a quick overview of the steps:
- Confirm your eligibility based on your service history and discharge type
- Request your Certificate of Eligibility (COE) online, through a lender, or by mail
- Choose a VA-approved lender and get pre-approved
- Find a home and sign a purchase agreement with a VA escape clause
- Complete the VA appraisal and underwriting process
- Pay the VA funding fee (or confirm your exemption)
- Close on your home and move in
The VA home loan program was created by the original G.I. Bill in 1944. Since then, it has helped more than 28 million veterans and service members become homeowners. It's a lifetime benefit — meaning you can use it more than once.
The biggest advantages over a conventional mortgage:
- No down payment required in most cases
- No private mortgage insurance (PMI)
- Competitively low interest rates
- No prepayment penalty
Despite all that, it remains one of the most underused benefits available to American military families.
I'm Larry Fowler, publisher of the USMilitary.com Network since 2007, and I've spent nearly two decades helping veterans navigate benefits like how to apply for a VA home loan — cutting through the confusion so you can act with confidence. Let's walk through everything you need to know.
What is a VA Loan and What Are the Benefits?
Before we dive into the step-by-step application process, let's look at what makes this benefit so powerful. A VA loan is a mortgage loan issued by private lenders—such as banks, credit unions, or mortgage companies—and partially guaranteed by the Department of Veterans Affairs.
This government backing reduces the risk for lenders, which allows them to offer you incredibly favorable terms. The primary benefits of a VA-backed loan include:
- Zero Down Payment: For most homebuyers, saving up a 5% to 20% down payment is the biggest barrier to homeownership. With a VA loan, you can finance 100% of the home's purchase price.
- No Private Mortgage Insurance (PMI): On conventional loans, if you put down less than 20%, you must pay a monthly PMI fee. VA loans never require PMI, saving you hundreds of dollars every month.
- Highly Competitive Interest Rates: Because of the government guarantee, VA loan interest rates are typically lower than those of conventional mortgages.
- No Prepayment Penalties: You can pay off your loan early or make extra payments without facing financial penalties.
For a deeper dive into these perks and how they stack up against other financing options, check out our guide on VA Loan vs Conventional Loan and explore Your Guide to VA Home Loans from Service to Homeownership. To learn more about the program directly from the source, you can also visit the VA Home Loans - Veterans Benefits Administration portal.
Key Differences: Purchase Loans, IRRRL, Cash-Out Refinance, and NADL
The VA offers several different types of home loan programs depending on whether you are buying a home, refinancing, or have specific direct lending needs.
- VA Purchase Loan: The standard loan used to buy, build, or adapt a primary residence.
- Interest Rate Reduction Refinance Loan (IRRRL): Also known as a "VA Streamline Refinance," this allows you to refinance an existing VA loan to a lower interest rate with minimal paperwork and no new COE required.
- Cash-Out Refinance: This option allows you to replace your current mortgage (VA or non-VA) with a new VA loan, pulling out cash from your home's equity to pay off debt, make home improvements, or cover other expenses.
- Native American Direct Loan (NADL): A specialized program where the VA acts as the direct lender for eligible Native American veterans to buy, build, or improve homes on federal trust land.
To help you decide which path is right for you, we have put together a quick comparison table:
| Loan Type | Best For | Down Payment | Key Requirement |
|---|---|---|---|
| VA Purchase Loan | Buying or building a primary home | 0% | Valid COE, meets lender credit/income standards |
| IRRRL (Streamline) | Lowering rate on existing VA loan | N/A | Existing VA loan, lower monthly payment |
| Cash-Out Refinance | Accessing home equity for cash | N/A | Home equity, meets credit/income standards |
| NADL | Native American veterans on trust land | 0% | Participating tribal organization agreement |
If you already own a home and are looking to optimize your mortgage, read up on Unlock Your Home's Potential VA Loan Refinance Strategies to see how refinancing can work for you.
VA Loan Eligibility and Minimum Service Requirements
To qualify for a VA home loan, you must first establish that you meet the minimum service requirements set by the Department of Veterans Affairs. Your eligibility is largely determined by your service history, duty status, and discharge type.
Generally, you must have served on active duty for a minimum period, which varies depending on when you served. Additionally, your discharge must be "other than dishonorable." To verify your standing and begin, you will want to review the official guidelines on Eligibility For VA Home Loan Programs | Veterans Affairs and read our comprehensive walkthrough on How to Qualify for a VA Home Loan.
Minimum Service Requirements Across Eras and Branches
The minimum active-duty service requirements depend heavily on the era in which you served:
- Gulf War Era (August 2, 1990, to present): You must have completed 24 continuous months of active duty, or at least 90 days if you were discharged for a service-connected disability, hardship, or reduction in force.
- Vietnam Era & Earlier Eras (e.g., WWII, Korean War): Generally, 90 days of active-duty service is required during wartime periods.
- Peacetime Eras: If your service fell entirely within peacetime periods between 1947 and 1990, the requirement is typically 181 continuous days of active duty.
- National Guard and Reserve Members: Historically, Guard and Reserve members needed at least 6 years of honorable service. However, eligibility rules now include National Guard members with at least 90 days of active service, including at least 30 consecutive days under Title 32 (specifically Sections 316, 502, 503, 504, or 505).
To ensure you meet the exact criteria for your specific service window, consult the detailed list of 2026 VA Home Loan Requirements.
How to Apply for a VA Home Loan with a Non-Standard Discharge
If you received an other-than-honorable (OTH), bad conduct, or dishonorable discharge, or if you do not meet the minimum service requirements, you may still have options.
First, you can apply for a discharge upgrade through your military branch's review board if you believe your discharge characterization was unjust or resulted from factors like Post-Traumatic Stress Disorder (PTSD) or Traumatic Brain Injury (TBI).
Second, you can request a VA Character of Discharge review. The VA will evaluate your service records to determine if your service can be considered "honorable for VA purposes," which could unlock your home loan benefits even if your official discharge certificate says otherwise.
How to Apply for a VA Home Loan as a Surviving Spouse
Surviving spouses of veterans can also qualify for VA home loan benefits. To be eligible, you must meet one of the following criteria:
- You are the unremarried surviving spouse of a veteran who died in service or from a service-connected disability.
- You are the spouse of an active-duty service member who is currently listed as Missing in Action (MIA) or a Prisoner of War (POW) for at least 90 days.
- You receive Dependency and Indemnity Compensation (DIC) benefits.
To apply, you will need to submit VA Form 26-1817 along with your spouse's DD Form 214 and a copy of your marriage certificate to verify your eligibility.
How to Apply for a VA Home Loan: Step-by-Step Guide
Now that you know the basics of eligibility, let's walk through the actual homebuying and application process. Getting pre-approved and organized early will save you time and keep stress levels low. If you want to jumpstart the process, check out our guide on how to Quickly Qualify VA Home Loan.
Step 1: Request Your Certificate of Eligibility (COE)
Your Certificate of Eligibility (COE) is the official document that proves to a lender that you qualify for the VA home loan benefit. There are three main ways to request your COE:
- Through Your Lender: This is by far the fastest and easiest method. Most VA-approved lenders have access to the VA's Web LGY system and can retrieve your COE instantly. In fact, nearly all COE requests come electronically, and about two-thirds get issued immediately.
- Online via eBenefits: You can log into the VA's eBenefits portal and apply for your COE yourself.
- By Mail: You can print out and complete VA Form 26-1880 (Request for a Certificate of Eligibility) and mail it to the VA, though this method takes much longer.
For more details on this critical first step, visit Certificate of Eligibility - VA Home Loans.
Step 2: Gather Your Required Documents
To secure your COE and complete your loan application, you must gather specific military and financial documents:
- Veterans: DD Form 214 (showing the character of service and narrative reason for separation).
- Active-Duty Service Members: A current statement of service signed by your commander or adjutant showing your full name, Social Security Number, date of birth, entry date, and any lost time.
- National Guard/Reserve Members: NGB Form 22 (Report of Separation and Record of Service) or a retirement points statement (such as DA Form 5016).
Lenders will also require standard financial documentation, including recent pay stubs, W-2 forms, tax returns, and bank statements.
Step 3: Find a Lender and Get Pre-Approved
The VA does not set interest rates or make lending decisions directly; private lenders do. Because of this, interest rates, closing costs, and underwriting standards can vary significantly from one lender to another.
It is highly recommended that you shop around and compare loan estimates from at least three different VA-approved lenders. To help narrow down your search, review our list of the Top 7 VA Home Loan Lenders and read up on How to Get the Best VA Home Loan Rate.
Fun Fact: As of June 2026, Navy Federal Credit Union remains a top 10 VA Lender by overall volume and total loan amount, making them a great starting point for many military families. In fact, 2,920 Veterans started their quote online today, proving how active this market is.
Step 4: Work with an Agent and Find Your Home
Once you have your pre-approval letter in hand, it's time to find a real estate agent. Look for an agent who has extensive experience with VA transactions. They will understand the unique timelines, appraisal guidelines, and how to write a competitive offer.
When you find the right home and write a purchase agreement, make sure your agent includes the VA escape clause (also known as the VA Option Clause). This clause legally protects you, allowing you to back out of the contract and retrieve your earnest money deposit if the home's appraised value comes back lower than the agreed-upon purchase price.
Additionally, while the VA requires an appraisal, you should always order a separate, comprehensive home inspection to check for hidden structural, electrical, or plumbing issues.
Understanding Lender Requirements, Appraisals, and Fees
While the VA sets the baseline eligibility rules, private lenders add their own requirements (known as "overlays") to protect their investments. Understanding these financial benchmarks will make your underwriting process much smoother.
Credit Scores, Debt-to-Income, and Residual Income
Although the VA does not enforce a strict minimum credit score, most lenders prefer to see a FICO score of at least 620. However, some lenders may accept lower scores if you have strong compensating factors.
Lenders will also evaluate your:
- Debt-to-Income (DTI) Ratio: This compares your monthly debt payments to your gross monthly income. While the VA's preferred DTI limit is 41%, you can still qualify with a higher ratio if you meet the residual income requirements.
- Residual Income: This is a unique VA underwriting metric. It calculates the amount of discretionary income you have left over each month after paying all major expenses (mortgage, taxes, insurance, credit cards, and estimated utility costs). This cushion ensures you can comfortably afford daily necessities like food and gas, reducing the likelihood of loan default.
The VA Appraisal Process and Low Valuations
Once your offer is accepted, your lender will order a VA appraisal. The appraiser—who is an independent professional assigned by the VA on a rotating basis—has two jobs: estimate the home's market value and verify that it meets the VA's Minimum Property Requirements (MPRs). MPRs ensure the home is safe, structurally sound, and sanitary.
If the appraisal comes in below the purchase price, you have a few options:
- Request a Reconsideration of Value (ROV): You and your agent can submit comparable home sales to prove the home is worth more.
- Renegotiate the Price: Ask the seller to lower the purchase price to match the appraised value.
- Pay the Difference: You can choose to pay the difference between the appraisal and the purchase price in cash at closing.
- Walk Away: Use the VA escape clause to cancel the contract and keep your deposit.
The VA Funding Fee and Exemptions
The VA funding fee is a one-time fee paid directly to the Department of Veterans Affairs to help sustain the home loan program for future generations. The fee is a percentage of your total loan amount and varies based on your service type, down payment size, and whether it is your first or subsequent time using the benefit.
For first-time use with 0% down, the funding fee is typically 2.15% for active duty and veterans.
Who is exempt from the VA funding fee?
You do not have to pay the funding fee if you:
- Receive VA compensation for a service-connected disability.
- Are eligible to receive disability compensation but receive retirement pay instead.
- Are an eligible surviving spouse.
- Are a Purple Heart recipient active-duty service member.
To see how disability ratings impact your loan terms, read our guide on the 100 Percent Disabled Veteran Home Loan.
Managing Your Benefit: Restoring Entitlement and Avoiding Foreclosure
Your VA loan benefit is not a one-and-done deal. It is a lifetime asset that you can manage, restore, and protect. For a complete understanding of how this works, take a look at our resource on VA Loan Entitlement.
How to Restore and Reuse Your VA Loan Entitlement
Your "entitlement" is the specific dollar amount the VA guarantees to your lender. If you have "full entitlement," there is no limit on how much you can borrow without a down payment (provided you qualify financially).
If you use your benefit and want to buy another home later, you can restore your entitlement in a few ways:
- Sell and Pay Off: Sell the home and pay off the VA loan in full.
- One-Time Restoration: Pay off the VA loan in full but keep the property (you can do this once).
- Loan Assumption: Have an eligible veteran assume your loan and substitute their entitlement for yours. To learn more about how this works, read Can a VA Loan Be Assumed by a Non-Veteran.
Steps to Avoid Foreclosure During Financial Hardship
If you ever experience financial difficulties that make it hard to pay your mortgage, the VA offers robust foreclosure avoidance assistance.
Do not wait until you miss a payment to take action. You can contact a specialized VA loan technician at 877-827-3702 for direct support. They can help you negotiate with your lender to establish:
- Repayment Plans: Spreading out missed payments over time.
- Loan Modifications: Adjusting your loan terms or interest rate to lower your monthly payment.
- Forbearance: Temporarily pausing or reducing your payments while you get back on your feet.
Frequently Asked Questions About VA Loans
Can I get a VA loan with no down payment?
Yes! One of the biggest advantages of the VA loan program is the 0% down payment option. As long as you have remaining entitlement and the purchase price does not exceed the home's appraised value, you can secure 100% financing.
How long does the VA loan application process take?
On average, a VA loan takes 30 to 45 days to close once you are under contract. This timeline is highly comparable to conventional and FHA mortgages. Working with an experienced VA lender and having your documents ready early can speed this up.
Does the VA set a minimum credit score?
No, the VA does not establish a minimum credit score. However, private lenders who fund the loans almost always set their own minimums, which typically hover around a 620 FICO score.
Conclusion
Taking advantage of your hard-earned VA home loan benefit doesn't have to be a headache. By understanding the eligibility rules, securing your COE early, and working with experienced professionals, you can navigate the path to homeownership with complete confidence.
At USMilitary.com, we are proud to serve as your central hub for military resources, financial guidance, and benefit updates. If you are ready to take the next step on your homebuying journey, visit our USMilitary.com VA Home Loans Hub to connect with trusted lenders and start your pre-approval today!