
Why a Military Discount Mortgage Could Save You Thousands
A military discount mortgage is one of the most powerful financial benefits available to U.S. service members, veterans, and their families. Here's a quick look at the main options:
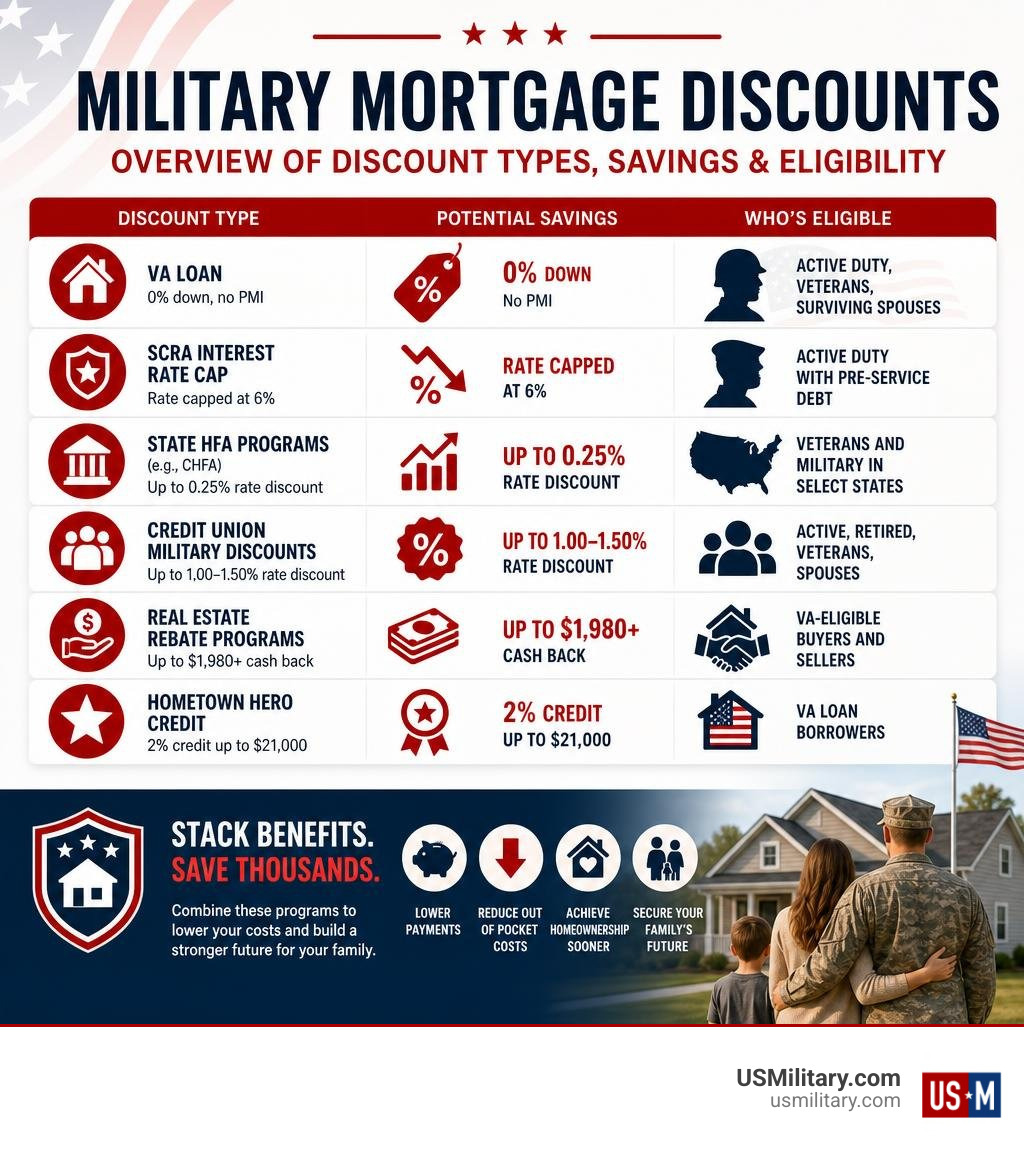
| Benefit | Who It's For | Key Savings |
|---|---|---|
| VA Loan | Active duty, veterans, surviving spouses | 0% down, no PMI |
| SCRA Interest Rate Cap | Active duty with pre-service debt | Rate capped at 6% |
| State HFA Programs (e.g., CHFA) | Veterans and military in select states | Up to 0.25% rate discount |
| Credit Union Military Discounts | Active, retired, veterans, spouses | Up to 1.00–1.50% rate discount |
| Real Estate Rebate Programs | VA-eligible buyers and sellers | Up to $1,980+ cash back |
| Hometown Hero Credit | VA loan borrowers | 2% credit up to $21,000 |
Buying a home is a major milestone — and military families face unique challenges getting there. The good news? The system is stacked in your favor if you know where to look.
Most service members know about VA loans. Far fewer know they can stack those benefits with state programs, lender discounts, and real estate rebates to save even more. This guide breaks it all down in plain language.
I'm Larry Fowler, publisher of NavySeal.com & USMilitary.com — a network I've run since 2007 to help active duty and veteran communities navigate benefits like the military discount mortgage. Over nearly two decades, I've tracked how these programs evolve and helped connect hundreds of thousands of service members with the resources they need to make smart financial decisions.
Glossary for military discount mortgage:
- VA Mortgage Lenders That Army Veterans & Active Prefer Most
- Unbiased Unpaid Rocket Mortgage Reviews For VA Loans
- Unbiased Unpaid Veterans United Mortgage Lender Reviews
Understanding the Military Discount Mortgage: Benefits and Options
When we talk about a military discount mortgage, we are referring to a broad ecosystem of home financing programs designed specifically for those who serve. These are not just standard loans with a tiny discount tacked on at the end; they are highly specialized financial products built to eliminate the massive upfront barriers that typically keep families from buying a home.

At the heart of this system is the federally backed VA loan program. Established during World War II, the VA loan has evolved into the gold standard of home financing. Because the Department of Veterans Affairs guarantees a portion of each loan, private lenders are willing to offer incredibly competitive interest rates and terms.
Through our comprehensive resources on VA Home Loans, we have helped thousands of families understand that this benefit is a lifetime right. It is not a one-time-only deal. You can use your entitlement to purchase a home, sell it, restore your entitlement, and use it again. In fact, under certain rules, you can even have multiple active VA loans at the same time.
How a Military Discount Mortgage Compares to Conventional Loans
To truly appreciate the value of a military discount mortgage, it helps to look at the numbers. When you buy a home with a conventional mortgage, you are immediately hit with two major financial hurdles: the down payment and private mortgage insurance (PMI).
With a conventional loan, if you cannot put down 20% of the home's purchase price, you are forced to pay monthly PMI. This insurance protects the lender, not you, yet it can easily add $100 to $300 to your monthly payment. On top of that, coming up with a 20% down payment on a $400,000 home means saving a staggering $80,000 in cash.
A VA loan completely sweeps these obstacles off the table. It offers 100% financing, meaning you can buy a home with $0 down. It also completely outlaws PMI, saving you thousands of dollars over the life of your loan.
| Feature | VA Loan | Conventional Loan |
|---|---|---|
| Down Payment | 0% required | Typically 3% to 20% |
| PMI Required? | No | Yes (if down payment is under 20%) |
| Interest Rates | Generally 0.25% to 0.50% lower | Standard market rates |
| Credit Requirements | More flexible | Stricter |
| Government Guarantee | Yes (by the VA) | No |
For a deeper dive into how these two paths diverge, check out our comparison on VA Loan vs Conventional Loan.
Steps to Apply for Your Military Discount Mortgage
Getting your hands on a military discount mortgage is a straightforward process, but you must complete the steps in the correct order to avoid delays.
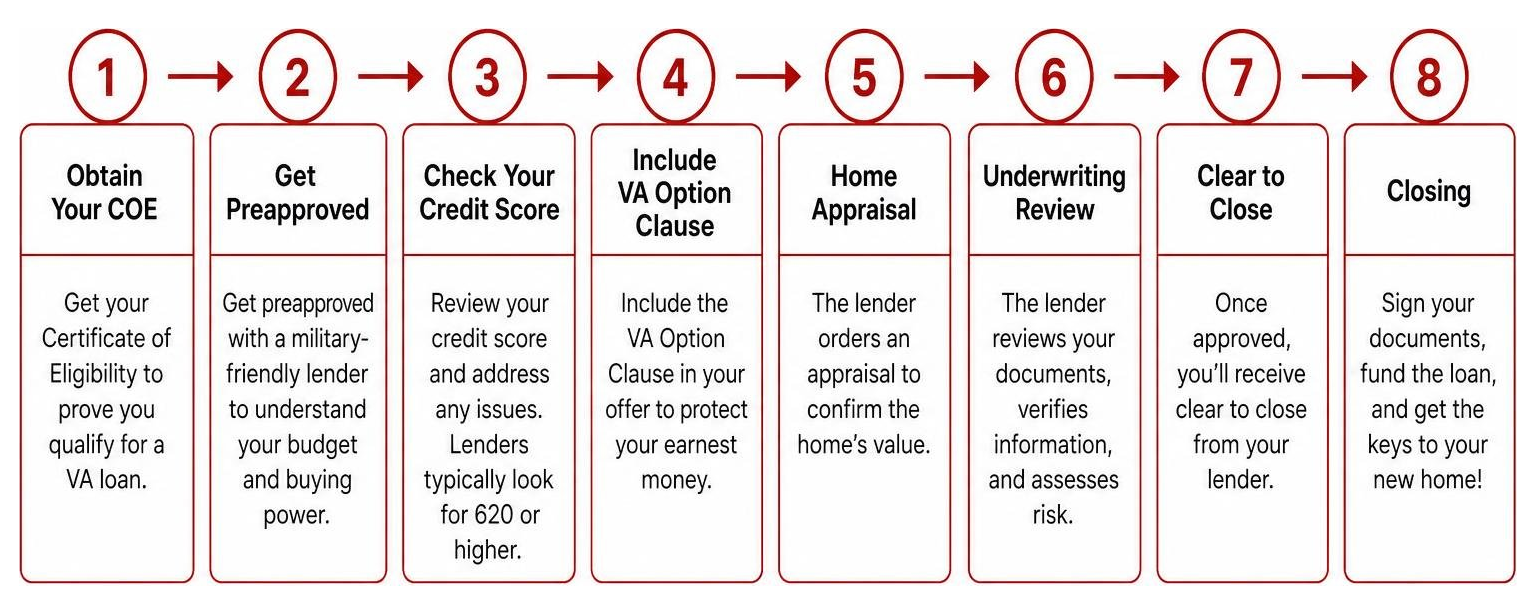
- Obtain Your Certificate of Eligibility (COE): This is the golden ticket. The COE proves to the lender that you meet the service requirements for a VA-backed loan. You can secure this document online through the VA's eBenefits portal, or you can have an approved lender retrieve it for you.
- Get Mortgage Preapproval: Before you start falling in love with houses on Zillow, you need to know your budget. Getting preapproved by a military-friendly lender gives you a clear picture of your buying power and shows sellers you are a serious buyer.
- Check Your Credit Score: While the VA does not set a strict minimum credit score, individual lenders (known as overlays) do. Most lenders look for a score of at least 620, though some will go lower.
- Include the "VA Option Clause": When you make an offer on a home, your real estate agent must include this protective clause. It ensures that if the home appraises for less than the purchase price, you can walk away with your earnest money deposit fully intact.
For a detailed, step-by-step walkthrough of this process, read our guide on How to Apply for a VA Home Loan.
Specialized Military Mortgage Options and Alternatives
While the federal VA loan is the most popular route, it is far from the only military discount mortgage option on the table. Several private lenders and credit unions offer proprietary alternatives designed for unique situations.
For example, Navy Federal Credit Union offers a specialized program called the Military Choice Loan. This is an excellent alternative for active duty, reservists, or veterans who have already exhausted their VA loan entitlement or want to buy a home with a non-spouse co-borrower (which is heavily restricted under standard VA rules). You can learn more about this directly through Navy Federal's Military Choice Loan and explore other Mortgage Options for Military Members.
Additionally, regional financial institutions often run exclusive promotions. Evergreen Credit Union, for example, offers a generous 1.00% interest rate discount on loans for active duty, retired military, honorably discharged veterans, and military spouses. By pairing these private programs with your federal benefits, you can customize a mortgage strategy that fits your exact financial profile.
VA Loan Eligibility and the Game-Changing 14-Day Rule
To qualify for a standard VA loan, you must meet minimum active service requirements. Historically, these rules were straightforward for active-duty personnel but left many National Guard and Reserve members in a frustrating "waiting room" when it came to homeownership.

Fortunately, legislative updates have dramatically expanded access, ensuring that more service members can transition from service to sanctuary. If you are looking to buy, we highly recommend reviewing our resources on Home Loans for Military to understand the full scope of your benefits.
Service Requirements for Active Duty and Veterans
For active-duty service members and veterans, eligibility is primarily determined by the timing and duration of your service:
- Active Duty: You are generally eligible after serving 90 continuous days of active duty.
- Peacetime Veterans: You typically need 181 continuous days of active service.
- Gulf War Era Veterans: The requirement is generally 24 continuous months of active service, or at least 90 days if you were discharged for a service-connected disability.
When applying, veterans will need to provide their DD214 discharge papers to verify the character of their service (which must be other than dishonorable) to secure their COE.
The New 14-Day Rule for Guard and Reserve Members
For decades, National Guard and Reserve members had to wait six long years to qualify for a VA loan, unless they were called up for at least 90 days of active service under federal Title 10 orders. This left hundreds of thousands of domestic-serving Guard and Reserve members without access to the same homebuying benefits as their active-duty counterparts.
Enter the 14-Day Rule under H.R. 6047 (the Home Affordability for Guard and Reserve Act).
This historic legislative shift slashes the eligibility requirement for National Guard and Reserve members to just 14 total days of qualifying service, which includes initial active duty for training and annual training.
This single policy change has opened the doors of homeownership to over 500,000 additional service members. Now, instead of waiting years or hoping for a federal deployment, a Guard member who has completed basic training and their initial school can immediately qualify for a 0%-down mortgage. To read the full breakdown of this monumental legislation, check out the detailed post on the 14-Day Rule for Guard and Reserve.
Stacking Extra Savings: Rebates, Credits, and State Programs
One of the biggest mistakes military homebuyers make is assuming they have to choose between a VA loan and other discounts. In reality, the smartest financial move you can make is stacking.
By combining your VA loan with lender credits, real estate commission rebates, and state-specific programs, you can walk away from the closing table with thousands of dollars remaining in your pocket.
Real Estate Commission Rebates and Lender Credits
Did you know you can get paid to buy a house? In many states, real estate commission rebates allow your buyer's agent to refund a portion of their commission directly to you at closing.
For instance, the Mutual of Omaha Mortgage rebate program offers an exclusive benefit where VA-eligible clients receive 22% of the real estate agent's commission back as a rebate (with an additional 3% automatically donated to the USO). On a $300,000 home purchase with a standard 3% commission, this translates to a $1,980 cash-back credit at closing.
Lenders also offer direct savings to capture your business. For example, Poli Mortgage Group offers military discounts that save families up to $875 on a home purchase and $250 on a home refinance.
Furthermore, programs like the Hometown Hero Credit provide military families with a massive 2% credit (up to $21,000) calculated on the loan amount. This credit can be used to pay off closing costs, buy down your interest rate, or pay down existing debts to help you qualify.
Down Payment Assistance and State-Specific Discounts
In addition to federal and private incentives, almost every state has its own Housing Finance Authority (HFA) offering localized perks.
A prime example is the Connecticut Housing Finance Authority (CHFA). Under their Military Homeownership Program, CHFA offers an additional 0.125% interest rate discount on top of their already below-market interest rates for veterans and active-duty service members. If you purchase a home in a federally designated "Targeted Area" of the state, that discount jumps to 0.25% (and the first-time homebuyer requirement is waived).
These state programs are incredibly valuable because they are often fully compatible with VA loans. By layering a state interest rate discount on top of a 0%-down VA loan, you secure an incredibly low monthly payment for the next 30 years.
Servicemembers Civil Relief Act (SCRA) Mortgage Protections
While a military discount mortgage helps you buy a home, the Servicemembers Civil Relief Act (SCRA) is designed to help you keep it. The SCRA is a powerful federal law that provides wide-ranging financial and legal protections to active-duty service members, ensuring they can focus on their mission without worrying about financial ruin back home.
The 6% Interest Rate Cap on Pre-Service Debt
One of the most valuable provisions of the SCRA is the 6% interest rate cap. Under federal law, any debt you incurred before entering active duty — including mortgages, credit cards, car loans, and student loans — must be capped at a maximum interest rate of 6% during your period of active service.
If you bought a home as a civilian with an 8% interest rate and are subsequently called to active duty, your mortgage servicer is legally required to lower your rate to 6%.
This is not a deferral; the lender must permanently forgive the excess interest, and your monthly payment must be reduced accordingly. To learn more about how this applies to your specific loan, you can review the Castle & Cooke Mortgage SCRA FAQs.
Foreclosure and Eviction Protections for Active Duty
The SCRA also provides robust protections against foreclosure. Without a court order, a lender cannot foreclose on a home owned by an active-duty service member if the mortgage was secured before their military service began.
These protections apply during your entire period of active duty and extend for one full year after your service ends. This gives transitioning service members a vital breathing room period to adjust back to civilian life and stabilize their finances without the looming threat of losing their home.
Frequently Asked Questions About Military Mortgages
Navigating the mortgage market can be confusing. Here are clear, straightforward answers to the most common questions military homebuyers ask.
What is the new 14-Day Rule for Guard and Reserve members?
The 14-Day Rule is a major legislative update under H.R. 6047 that allows National Guard and Reserve members to qualify for a VA home loan after just 14 days of qualifying service (including training). This replaces the old, restrictive rule that required six years of service or 90 days of active federal deployment. If you want to see how quickly you can get started, read our guide on how to Quickly Qualify VA Home Loan.
Can I get a military discount mortgage with zero down payment?
Yes! The VA loan program is famous for offering 100% financing, meaning you do not have to put a single penny down to purchase a primary residence. To see how zero down payment affects your monthly mortgage budget, play around with our VA Loan Payment Calculator.
How do SCRA protections lower my existing mortgage rate?
If you obtained a mortgage before entering active duty, the SCRA legally caps your interest rate at 6% for the duration of your active service. To get this benefit, you simply need to submit a written request and a copy of your military orders to your mortgage servicer.
Conclusion
Securing a military discount mortgage is about more than just finding a place to live — it is about building long-term wealth and establishing a sanctuary for your family. By combining the unmatched benefits of a VA loan with state programs, lender credits, and the legal protections of the SCRA, you can save tens of thousands of dollars over the life of your homeownership journey.
At USMilitary.com, we are dedicated to serving those who serve. Whether you are active duty, a veteran, or a Guard/Reserve member utilizing the new 14-Day Rule, we are here to provide the unbiased guidance and resources you need to succeed.
Ready to take the next step toward your dream home? Secure your military home benefits today and let us help you unlock the savings you have rightfully earned.







