Comparing Top Military Loan Options for Active Duty and Veterans
When you are weighing your military loan options, it quickly becomes clear that borrowing money in the armed forces isn't a one-size-fits-all proposition. Whether you are an active duty Navy SEAL preparing for deployment, an Air Force mechanic dealing with a sudden transmission breakdown, or a recently discharged veteran consolidating credit cards, the borrowing mechanism you select will drastically shape your financial future.
To help you compare the primary paths, we have broken down how personal unsecured debt, zero-interest emergency grants, and asset-collateralized loans stack up against each other:
| Feature / Metric | Unsecured Personal Loans | Emergency Relief Loans | Secured / Asset-Backed Loans |
|---|---|---|---|
| Typical APR Range | 8.74% – 35.95% | 0.00% (Interest-Free) | Variable or Fixed (0.50% auto-pay discount) |
| Maximum Loan Amount | $250 up to $150,000 | $1,000 (Falcon) up to $2,000 (AER Commander Referral) | Up to 90% of mutual funds or 100% of CD value |
| Typical Repayment Terms | 9 to 180 months | 3 to 12 months | 6-month single-pay or 60-month installment |
| Collateral Required? | None | None | Yes (CDs, savings accounts, non-taxed mutual funds) |
| Best Used For | Debt consolidation, home upgrades, major purchases | Emergency travel, medical co-pays, basic utilities | PCS transition gaps, building credit safely |
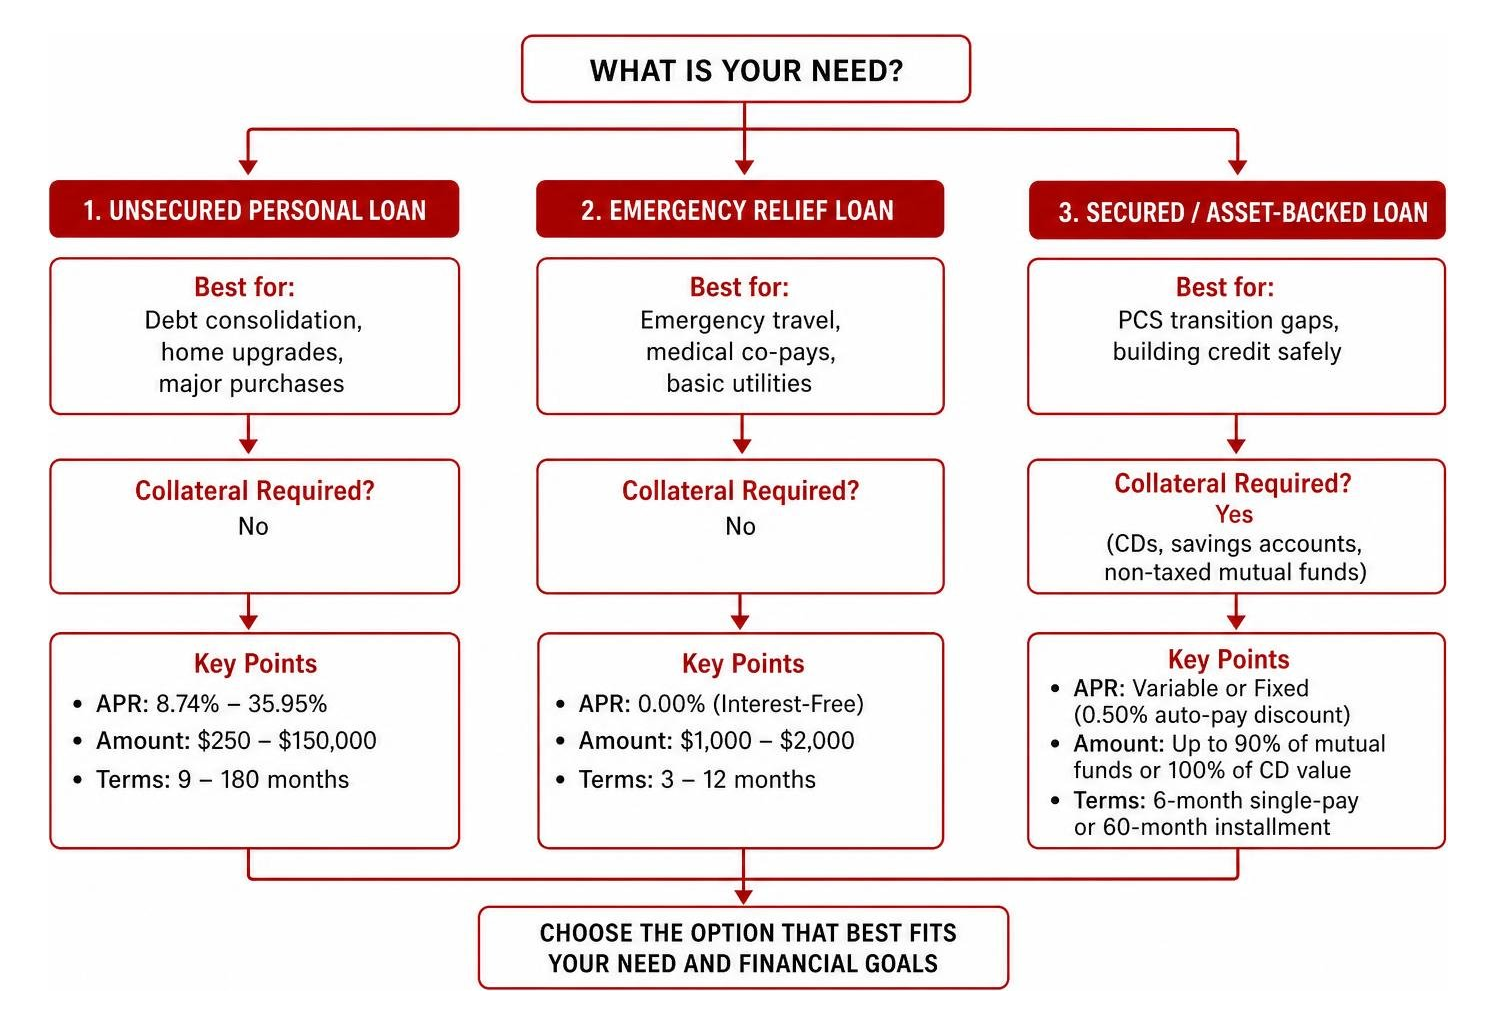
Unsecured Personal Military Loan Options
Unsecured personal loans give you a lump-sum payout with fixed interest rates and predictable monthly payments without requiring you to pledge your car or home as collateral. These loans are a common choice for consolidating high-interest credit card balance transfers, funding home renovations, or managing unexpected relocation gaps during permanent change of station (PCS) orders.
Military credit unions and specialized banks frequently lead the market with lower interest rates and reduced fee structures compared to standard commercial institutions:
- Navy Federal Credit Union: Offers personal expense loans ranging from $250 to $150,000 with interest rates starting as low as 8.74% APR for repayment terms up to 36 months (and rates up to 18.00% APR depending on creditworthiness). Most personal loans fund in 24 hours or less, making them accessible when speed matters. Loans over $50,000 require a qualified co-applicant.
- Armed Forces Bank: Provides Military Personal Loans ( Access Loans) ranging from $250 to $15,000 with repayment terms extending between 9 and 48 months. APRs range from 14.95% to 35.95%, tailored specifically to accommodate service members with limited credit history or lower credit scores. For instance, a representative $3,000 loan at a 15.94% APR over 24 months results in a monthly payment of $141.16. New customers are required to open a direct deposit checking account, and an origination fee of 10% of the loan amount or $100 (whichever is less) applies.
- AmeriCU Credit Union: Extends military-discounted lending across unsecured personal loans, vehicle loans, and home improvement financing. In 2025 alone, AmeriCU delivered over $17.3 million in military-discounted loans, offering perks like receiving military pay one business day early through direct deposit and credit card pre-approvals up to $1,000 at account opening.
For an exhaustive breakdown of individual lender reviews, eligibility terms, and minimum credit cutoffs, check out our detailed guide to top military personal loan lenders.
Emergency and Relief Society Military Loan Options
Before you apply for a commercial unsecured personal loan, you should look into official military relief societies. Every military branch operates a dedicated, non-profit aid society designed to rescue service members from financial distress without burdening them with interest fees or debt traps.
These aid societies serve as a direct defense against predatory payday lenders who set up shop right outside base gates:
- Air Force Aid Society (AFAS) Falcon Loan: Designed specifically for active duty Air Force and Space Force members (as well as Reservists and Air National Guard personnel on extended Title 10 active duty over 15 days). The Falcon Loan provides an expedited, interest-free emergency loan up to $1,000 with zero administrative fees. Repayment is structured seamlessly through pay allotment over 3 to 12 months. Securing a Falcon Loan does not prevent an Airman from receiving Standard Assistance if a separate crisis emerges down the road.
- Army Emergency Relief (AER): Founded in 1942, AER has assisted more than 4 million Soldiers and dependents with over $2 billion in direct aid. Through the Commander's Referral Program, company commanders and First Sergeants can directly approve zero-interest loans up to $2,000. Soldiers who have completed AIT, served over a year, and maintained clean records can apply directly at an AER office without needing chain-of-command sign-off. AER covers expenses such as emergency travel, vehicle repair, lodging, cranial helmets, and spouse relicensing fees.
- Navy-Marine Corps Relief Society (NMCRS) & Coast Guard Mutual Assistance (CGMA): Reciprocal agreements exist across all branch aid societies. If you are a Navy SEAL or Marine deployed to a joint base without a local NMCRS office, you can access relief funds through an AER office or the American Red Cross.
Secured and Asset-Backed Loans
If you have established savings, certificates of deposit (CDs), or non-retirement investment accounts, secured personal loans offer a way to unlock cash at reduced interest rates.
Rather than liquidating your long-term investments and triggering capital gains or losing out on compound growth, you pledge those assets as collateral.
- Savings and Certificate-Secured Loans: Financial institutions like Navy Federal allow you to borrow against your certificate or share savings balance. Because the lender carries near-zero risk, your interest rate is pegged directly above the yield your account earns, usually with no credit check required.
- First Command Bank Asset-Backed Loans: First Command offers secured personal loans starting at $2,000 using non-tax-qualified mutual funds (up to 90% of value) or bank CDs (up to 100% of value) as collateral. Setting up automatic monthly payments yields a 0.50% APR discount.
- PCS Single-Pay Loans: For military families undergoing a hectic move, First Command provides a specialized 6-month single-pay loan. For example, a $10,000 PCS loan at 2.99% APR matures with a single balloon payment of $10,151.16 after 6 months, giving you time to receive government travel vouchers and dislocation allowances before settling the bill.
Key Protections and Legal Safeguards Under SCRA and MLA

When evaluating military loan options, you aren't just relying on lender goodwill — federal law grants active duty service members specific rights that cap interest rates and eliminate predatory terms.
The Servicemembers Civil Relief Act (SCRA)
The SCRA provides significant financial relief on consumer debt, credit cards, mortgages, and personal loans entered into prior to entering active duty. Key benefits include:
- 6% Interest Rate Cap: Under the SCRA, any pre-service debt must be capped at a maximum annual interest rate of 6% upon written request by the service member, with orders attached. Lenders must forgive (not defer) any interest charged above 6% retroactively.
- Protection Against Default Judgments and Repossessions: Lenders cannot repossess property or motor vehicles, or foreclose on a home, for non-payment without a court order while you are on active duty service.
The Military Lending Act (MLA)
While the SCRA covers pre-service debt, the MLA protects active duty personnel, National Guard or Reserve members on active duty orders for over 30 days, and their dependents on debts incurred while actively serving.
- 36% Military Annual Percentage Rate (MAPR) Cap: The MLA caps the MAPR at 36%. Unlike standard APR calculations, the MAPR calculation incorporates credit insurance premiums, finance charges, debt cancellation fees, and application fees.
- No Mandatory Allotments: A lender cannot force you to set up an automatic military pay allotment as a mandatory condition for loan approval.
- No Prepayment Penalties: Under the MLA, you retain the legal right to pay off personal debt early without incurring early termination or prepayment penalty fees.
Career Commissioning and Service Academy Loan Programs
One of the most competitive financial vehicles in the entire military ecosystem is the commissioning loan offered to service academy cadets, ROTC students, and officer candidates. Often referred to colloquially at West Point as the "cow loan," these unsecured signature loans are designed to furnish young officers with initial funding for military uniforms, gear, security deposits, or cheap transport before active duty pay begins.
- Navy Federal Career Kickoff Loan:
- Service Academy Cadets: Juniors and seniors at USMA, USNA, USAFA, USCGA, and USMMA can borrow up to $36,000 at 0.75% APR over a 60-month term, with payments deferred up to 90 days post-graduation.
- ROTC, OCS/OTS, Warrant Officers, and LDOs: Eligible candidates within 12 months before or after commissioning can access up to $25,000 at 2.99% APR over a 60-month term. Repayment can be deferred up to 180 days post-commissioning (or 45 days after origination if already commissioned), creating a fixed monthly payment of $449.67 with total finance charges under $1,980.
- USAA Career Starter Loan: Offers pre-commissioned officers $25,000 to $35,000 at low interest rates historically ranging between 0.5% and 2.99%, with payments deferred until 6 months post-commissioning.
Crucial Caveat: To maintain these promotional rates, borrowers must establish and maintain direct deposit into a checking account with the issuing credit union within 90 days. Losing direct deposit status or defaulting will cause the interest rate to revert to standard personal loan rates or trigger an 18% penalty rate. Additionally, military rules prohibit holding both a USAA Career Starter Loan and a Navy Federal Career Kickoff Loan simultaneously; loan proceeds from a new loan must be used to pay off the existing balance of the other.
For enlisted members entering service with existing educational debt, federal programs like the College Loan Repayment Program (LRP)) can serve as an effective alternative to private consolidation loans by funding up to $65,000 of qualifying student loan debt.
Evaluating Fees, APRs, and Deployment-Friendly Terms
Navigating military loan options requires evaluating the total cost of credit beyond the headline interest rate. A low nominal rate can quickly lose its appeal if hidden fees or rigid deployment terms work against you.
Origination Fees and Prepayment Penalties
Always review loan disclosures for origination fees. While military credit unions like Navy Federal charge $0 origination fees and $0 prepayment penalties, commercial lenders may deduct an origination fee directly from your principal before funding. For example, Armed Forces Bank assesses an origination fee of 10% or $100 (whichever is less). Paying off a loan early should always be free; verify that your contract explicitly permits penalty-free early payoff.
Deployment Flexibility and Account Controls
Deploying overseas on operational taskings — such as a Navy SEAL team deploying to a forward location — introduces distinct communication challenges. You need a lender that offers:
- Deployment Interest Adjustments: Card programs like the MILITARY STAR Card offer interest rate reductions during deployment upon sending activation orders to
[email protected]. - Power of Attorney (POA) Acceptance: Your lender must readily process paperwork executed by your spouse or designated agent holding a valid Special Power of Attorney while you are deployed.
- Automated Payment Discounts: Look for lenders offering a 0.25% to 0.50% APR discount for setting up recurring automated clearing house (ACH) payments from your checking account.
Debunking the "VA Personal Loan" Myth
A common misconception among service members is that the Department of Veterans Affairs offers government-backed personal loans for cash expenses or credit card payoffs. The VA does not issue or guarantee unsecured personal loans.
VA benefits are legally restricted to home mortgage products, cash-out mortgage refinances, education, and disability benefits. To clear up common misconceptions about government-backed financing, take a look at our guide on understanding VA personal loan myths.
Frequently Asked Questions About Military Loans
What is the maximum interest rate cap for active duty service members under federal law?
Under the Servicemembers Civil Relief Act (SCRA), financial obligations incurred prior to entering active duty are capped at a maximum interest rate of 6% per year. Any interest above 6% must be permanently forgiven by the creditor for the duration of active duty service.
For consumer loans obtained during active duty, the Military Lending Act (MLA) caps the Military Annual Percentage Rate (MAPR) at 36%, which includes mandatory finance charges, application fees, and ancillary credit insurance premiums.
Does the Department of Veterans Affairs directly offer personal loans?
No. The U.S. Department of Veterans Affairs (VA) does not offer, back, or guarantee unsecured personal loans. VA loan benefits are strictly limited to residential mortgages, home adaptation grants, and home equity cash-out refinances.
If you own a primary residence with accrued equity, you can utilize a VA Cash-Out Refinance to convert home equity into liquid cash at favorable mortgage rates. For a comprehensive walkthrough on buying a home or tapping your home equity, read our complete VA home buying guide.
How do military emergency relief loans differ from commercial personal loans?
Military emergency relief loans (such as the Air Force Aid Society Falcon Loan or Army Emergency Relief loans) are provided by non-profit relief societies dedicated solely to service members. They carry 0.00% APR interest, charge zero application or origination fees, and require no credit checks.
Repayment is handled via automatic military pay allotments over a 3-to-12-month period. Commercial personal loans, by contrast, are offered by profit-driven financial institutions, charge variable or fixed interest rates (ranging from 8.74% to 35.95%), evaluate credit scores, and may assess administrative or late fees.
Conclusion
Managing your financial readiness is just as critical as maintaining your combat readiness. By understanding the full spectrum of military loan options — from interest-free branch relief societies like AER and AFAS to low-APR credit union personal loans, career kickoff programs, and asset-backed financing — you can make smart choices that protect your monthly cash flow.
Always remember to leverage federal legal protections under SCRA and MLA, watch out for origination fees, and avoid borrowing money for unnecessary consumer purchases. When unexpected emergencies strike or major life events happen, choose the loan structure that serves your long-term wealth.
For more deep-dive guides on VA benefits, career transitions, and military financial planning, visit our USMilitary.com central resource portal today!