What You Need to Know About Military Pension Requirements (Quick Answer)

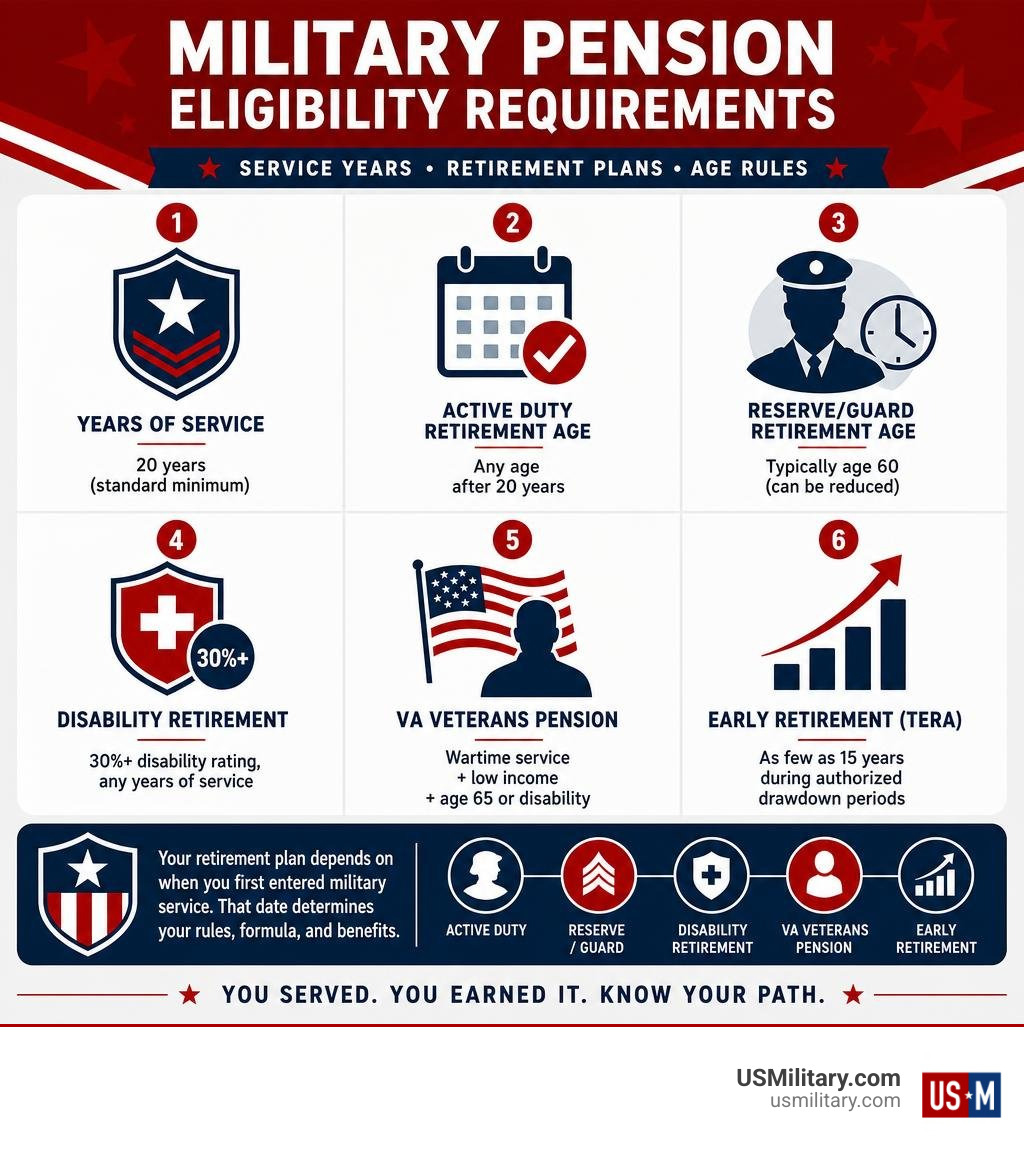
Understanding military pension requirements is the first step to securing the retirement benefits you've earned. Here's a fast overview:
| Requirement | Details |
|---|---|
| Years of Service | 20 years (standard minimum) |
| Active Duty Retirement Age | Any age after 20 years |
| Reserve/Guard Retirement Age | Typically age 60 (can be reduced) |
| Disability Retirement | 30%+ disability rating, any years of service |
| VA Veterans Pension | Wartime service + low income + age 65 or disability |
| Early Retirement (TERA) | As few as 15 years during authorized drawdown periods |
The retirement plan you fall under depends on when you first entered military service — and that one date can significantly change how your monthly pension is calculated.
Military retirement isn't a single program. It's a set of overlapping systems — each with its own rules, formulas, and timelines. Whether you're active duty, in the Reserves, a veteran with a disability, or a low-income wartime veteran, there's likely a pathway that applies to you.
But navigating all of it? That's where things get complicated fast.
This guide breaks down every major pension pathway in plain language — so you know exactly where you stand and what steps to take.
I'm Larry Fowler, publisher of the USMilitary.com Network since 2007, and I've spent nearly two decades helping service members and veterans cut through the confusion around VA benefits and military pension requirements. In this guide, I'll walk you through everything you need to know — from eligibility rules to the application process — so you can approach your retirement with confidence.
Military pension requirements terms at a glance:
Understanding the Core Military Pension Requirements
At its heart, the military retirement system is designed to reward long-term service and keep our armed forces young, vigorous, and competitive with the private sector. For the vast majority of service members, the golden key to unlocking a lifetime pension is the "20-year rule."
Whether you served on active duty or in the Reserve components, reaching 20 years of qualifying service is the standard benchmark. However, how those 20 years are measured—and when you actually start seeing that monthly check in your bank account—depends entirely on the nature of your service.
To help map out your timeline, look at the transition milestones outlined in our guide on The Golden Years: Countdown and Pension Eligibility Age Limits.
Active Duty vs. Reserve Service Rules
Active duty service members and reservists follow two very different paths to meet their military pension requirements.
For active duty personnel, the math is straightforward: you must accumulate 20 years of continuous active service. Once you hit that 20-year mark, you can retire and begin drawing your monthly pension immediately, regardless of your age. If you retire at age 38, your pension starts at age 38.
For members of the National Guard and Reserves, the system is based on "qualifying years" and retirement points. To earn a qualifying year for retirement, a reservist must earn at least 50 retirement points within their anniversary year. Points are accumulated through:
- Active duty service (1 point per day)
- Unit training assemblies or drills (typically 4 points per weekend)
- Professional military education
- Annual training periods
While reservists must still achieve 20 qualifying years to retire, they generally cannot begin receiving their pension payments until they reach age 60. This period between retiring from service and reaching pay eligibility is commonly referred to as the "gray area," and these retirees are known as "gray area reservists."
Exceptions to the 20-Year Rule: TERA and Chapter 61
While 20 years is the golden standard, the military does provide exceptions for early retirement under specific statutory authorities.
The first major exception is the Temporary Early Retirement Authority (TERA). TERA allows the Secretary of a military department to offer voluntary retirement to service members who have completed at least 15 but fewer than 20 years of active service. This authority is primarily used as a force-shaping tool during periods of military drawdown. Under TERA, your retirement pay is calculated using your actual years of service, but it is subject to a 1% reduction for each year you retire short of the standard 20-year mark.
The second major exception is medical retirement under Chapter 61 of Title 10, United States Code. If a service member is found unfit for continued duty due to a physical disability, and that disability is rated at 30% or higher by the military, they can be placed on the disability retirement list regardless of their total years of service. This means a service member with only 5 years of service could qualify for a lifetime military pension if their combat-related injuries or service-connected conditions meet the Chapter 61 criteria.
For the precise legal definitions governing these initial retirement entitlements, you can refer directly to the DoD Financial Management Regulation Volume 7B Chapter 1.
The Four Major Military Retirement Plans
Depending on the date you first contracted or enlisted—known as your Date of Initial Entry into Military Service (DIEMS)—you will fall under one of four distinct retirement systems.
| Retirement Plan | DIEMS Date Range | Standard Multiplier | Key Features |
|---|---|---|---|
| Final Pay | Before September 8, 1980 | 2.5% per year | Based on final basic pay; up to 100% at 40 years |
| High-36 | Sept 8, 1980 – July 31, 1986 | 2.5% per year | Based on average of highest 36 months of basic pay |
| CSB/REDUX | Aug 1, 1986 – Dec 31, 2017 | 2.0% to 2.5% | $30,000 Career Status Bonus at 15 YOS; reduced multiplier |
| Blended (BRS) | On or after January 1, 2018 | 2.0% per year | 1% automatic + 4% matching TSP; Continuation Pay |
Choosing the right path and understanding how your entry date impacts your lifetime earnings is a major part of The Golden Years: Navigating Your Active Duty Retirement Options.
Final Pay and High-36 Systems
If you joined the military before September 8, 1980, you are covered by the Final Pay System. This is the most generous legacy plan. Under this system, your retired pay base is your final monthly basic pay when you retire. Your pension is calculated by multiplying your final basic pay by 2.5% for each year of service. At 20 years, you receive 50% of your final pay; if you serve 40 years, you receive 100%.
For those who entered service between September 8, 1980, and July 31, 1986 (as well as those who entered later but did not elect the REDUX option), the High-36 System applies. Instead of using your final basic pay, your retired pay base is calculated by averaging the highest 36 months of basic pay you received during your career. The multiplier remains 2.5% per year of service, meaning a 20-year retiree still receives 50% of their High-36 average. This system protects the government against sudden, late-career rank promotions inflating lifetime pension payouts.
For a deeper dive into the history and legislative structure of these legacy systems, check out the Defense Primer: Military Retirement.
Blended Retirement System (BRS) and TSP Matching
The Blended Retirement System (BRS) represents the most significant shift in military retirement policy in generations. Applying to all service members who entered on or after January 1, 2018 (and those who opted in during the 2018 transition window), the BRS blends a traditional pension with a portable 401(k)-style investment account.
Under the BRS, the pension multiplier is reduced from 2.5% to 2.0% per year of service. This means that after 20 years, your defined pension benefit will equal 40% of your High-36 average, rather than the legacy 50%.
To make up for this 10% reduction, the government introduces matching contributions to your Thrift Savings Plan (TSP):
- 1% Automatic Contribution: After 60 days of service, the government automatically contributes 1% of your basic pay to your TSP, even if you contribute nothing.
- Up to 4% Matching: After two years of service, the government will match your personal TSP contributions dollar-for-dollar up to an additional 4%. This brings the total potential government contribution to 5%.
- Vesting: You are fully vested in the government’s matching contributions after completing two years of service.
The BRS also features Continuation Pay—a mid-career retention bonus offered between 8 and 12 years of service in exchange for a commitment to serve at least three additional years—and a flexible lump-sum payout option at retirement.
CSB/REDUX Plan and the Career Status Bonus
The CSB/REDUX plan was an option for service members who entered between August 1, 1986, and December 31, 2017. Upon reaching their 15th year of service, members could elect to receive a $30,000 upfront, taxable cash bonus called the Career Status Bonus.
The catch? In exchange for the quick cash, the member agreed to have their retirement multiplier reduced.
Under REDUX, the retirement pay multiplier is reduced by 1% for each year the member's service falls short of 30 years. At 20 years of service, instead of receiving 50% of their High-36 average, a REDUX retiree receives only 40%. The multiplier gradually "catches up" as service continues, reaching the full 75% at 30 years of service.
While the upfront cash was tempting for many, the long-term cost of the reduced multiplier made REDUX a less favorable financial option for most career service members.
How Your Retired Pay Base and Multiplier Are Calculated
Calculating your exact pension amount requires understanding two distinct variables: your retired pay base and your retired pay multiplier. The basic formula is:
$$\text{Monthly Retired Pay} = \text{Retired Pay Base} \times \text{Retired Pay Multiplier}$$
While this looks simple, the math behind determining your creditable service and applicable multiplier requires careful attention.
Calculating Creditable Service for Active Duty and Reserves
For active duty service members, calculating creditable service is a matter of counting calendar years and days of active duty. Every day of active service counts toward your retirement multiplier.
For National Guard and Reserve members, the calculation is point-based. To determine your "years of creditable service" for pay computation, you must take your total accumulated retirement points and divide them by 360.
For example, if a reservist retires with 20 qualifying years and has accumulated 3,600 total points:
$$\frac{3,600 \text{ points}}{360} = 10 \text{ years of creditable service for pay computation}$$
If this reservist is under the legacy High-36 plan (2.5% multiplier), their retired pay multiplier would be:
$$10 \text{ years} \times 2.5\% = 25\% \text{ of their High-36 average}$$
This explains why a reserve pension, while highly valuable, is typically smaller than an active-duty pension for the same number of calendar years.
Meeting Military Pension Requirements for Officers and Warrant Officers
Commissioned officers and warrant officers have additional statutory requirements to retire at their highest held rank.
To voluntarily retire as an officer and receive officer retirement pay, a regular commissioned officer must generally complete at least 20 years of active service, with at least 10 years of active commissioned service. If an officer fails to meet this 10-year requirement, they may be retired at the highest enlisted or warrant officer grade in which they served satisfactorily, and their pension will be calculated based on that lower pay grade.
During periods of military force drawdowns, this 10-year requirement can sometimes be reduced to 8 years by the Secretary of the military branch, but this is an exception rather than the rule.
Special Pension Pathways: Reservists, Disability, and Low-Income Veterans
Military service isn't one-size-fits-all, and neither are military pensions. The government has created distinct pathways to support those who served in the Reserves, those who were injured in the line of duty, and wartime veterans facing financial hardship later in life.
Reserve Component Age Reductions
As mentioned earlier, reservists normally have to wait until age 60 to start drawing their retired pay. However, federal law allows certain reservists to reduce this eligibility age.
Under Title 10 § 12731 Age and Service Requirements, a reservist's retirement age can be reduced by three months for every cumulative 90 days of qualifying active duty service performed after January 28, 2008. Qualifying service includes deployments, homeland security missions, and certain emergency active duty calls.
There is a hard statutory floor, however: the eligibility age cannot be reduced below age 50, regardless of how much active duty time the reservist has accumulated.
Chapter 61 Disability Retirement and VA Compensation
If you are medically retired under Chapter 61, your pension calculation is unique. You are permitted to choose the more financially favorable of two calculation methods:
- Longevity Formula: Your years of service multiplied by your standard multiplier (2.0% or 2.5%) times your retired pay base.
- Disability Formula: Your approved DoD disability percentage (capped at a maximum of 75%) multiplied by your retired pay base.
For example, if you have 10 years of service and receive a 60% DoD disability rating, you can choose to receive 60% of your retired pay base rather than the 25% you would get under the longevity formula.
However, receiving both military retirement pay and VA disability compensation can be tricky. By law, regular military retirement pay is offset dollar-for-dollar by any VA disability compensation you receive. To learn how to navigate these offsets and see if you qualify for programs that allow you to keep both payments, read our guide on Disabled Veteran Benefits: What You Need to Know.
VA Veterans Pension Requirements for Low-Income Wartime Veterans
Not to be confused with military retired pay (which is earned through a career in the service), the VA Veterans Pension is a needs-based benefit for low-income wartime veterans who are elderly or permanently disabled.
To meet the Eligibility For Veterans Pension requirements, a veteran must:
- Have not received a dishonorable discharge.
- Have served at least 90 days of active duty, with at least one day during an authorized wartime period (if enlisting before September 7, 1980). If enlisting after that date, they generally must have served 24 months or the full period for which they were called to active duty.
- Have a yearly family income and net worth that fall below limits set by Congress.
- Meet at least one of the following: be age 65 or older, have a permanent and total disability, be a patient in a nursing home, or be receiving Social Security Disability Insurance (SSDI).
The VA Veterans Pension provides monthly payments to bring the veteran's total income up to a level set by law, helping ensure that those who stood watch during wartime do not face poverty in their later years.
Protecting Your Benefits: COLA, SBP, and the Application Process
Getting your pension approved is only half the battle; the other half is protecting those benefits for yourself and your loved ones over the long haul.
Cost-of-Living Adjustments (COLA) and the Survivor Benefit Plan (SBP)
To ensure inflation doesn't eat away at your purchasing power, military retired pay is adjusted annually using Cost-of-Living Adjustments (COLA). These adjustments are tied directly to the Consumer Price Index, ensuring your monthly check rises along with the general cost of living.
Another critical protection tool is the Survivor Benefit Plan (SBP). When you retire, your military pension stops when you die. The SBP is an insurance-like program that allows you to elect to have a portion of your pension continue paying out to your designated beneficiaries (such as a spouse or children) after your death.
Under the SBP, the government will pay up to 55% of your elected base retired pay to your surviving beneficiaries. The premiums for SBP are automatically deducted from your monthly retirement check, making them pre-tax and highly cost-effective. For families planning their long-term financial security, understanding these survivor options is vital. You can explore the full spectrum of these protections in our article on Surviving Spouse VA Benefits.
Step-by-Step Guide to Applying for Your Pension
Your military pension will not start automatically. You must actively apply for it. To ensure your first check arrives on time, follow this step-by-step transition timeline:
- Pre-Separation Counseling (12 to 24 Months Out): Attend mandatory pre-separation briefings with your installation's transition assistance office. This is where you will review your service record and verify your DIEMS date.
- Schedule Your Final Physical (90 to 180 Days Out): Schedule and complete your separation history and physical examination. This documentation is critical if you plan to file for VA disability compensation.
- Complete Form DD-2656 (60 to 90 Days Out): This is the single most important form for your retirement. On Form DD-2656 (Data for Payment of Retired Personnel), you will select your SBP coverage options, designate your beneficiaries, set up federal tax withholding, and provide your direct deposit banking information.
- Submit Retirement Packet: Submit your completed DD-2656, retirement orders, and statement of service to your branch's human resources command or finance center.
- Update myPay: Ensure your contact information and mailing address are completely up to date in the Defense Finance and Accounting Service (DFAS) myPay system.
Frequently Asked Questions About Military Pensions
How long does it take to receive the first military retirement check?
Assuming all of your paperwork—especially Form DD-2656—was submitted correctly and on time, you can typically expect your first military retirement check to arrive 30 to 45 days after your official retirement date. DFAS processes payments on the first business day of each month for the preceding month.
Can you receive both military retirement pay and VA disability compensation?
Yes, but it depends on your specific circumstances. Historically, a dollar-for-dollar offset applied. However, Congress has established two concurrent receipt programs:
- Concurrent Retirement and Disability Pay (CRDP): Allows eligible retirees to receive both full military retired pay and full VA disability compensation. To qualify, you must be a 20-year retiree (active or reserve) with a service-connected disability rating of 50% or higher.
- Combat-Related Special Compensation (CRSC): A tax-free monthly payment that restores offset retired pay for retirees who have combat-related disabilities rated at 10% or higher. This is open to all retirees, including Chapter 61 medical retirees with fewer than 20 years of service.
What disqualifies a veteran from receiving a military pension?
A military pension can be delayed, reduced, or completely disqualified under certain conditions:
- Discharge Characterization: Receiving a Dishonorable or Bad Conduct discharge via a court-martial will disqualify you from receiving retired pay.
- Incarceration: Your pension payments can be suspended if you are incarcerated for more than 60 days following a felony conviction, though payments can sometimes be resumed or apportioned to your dependents during your confinement.
- Failure to Meet Commissioned Time: As an officer, failing to meet the 10-year active commissioned service rule will disqualify you from retiring at your officer rank.
Conclusion
Securing your military pension is the culmination of a career spent in service to our nation. Whether you are navigating the traditional High-36 system, maximizing your TSP matches under the Blended Retirement System, or calculating reserve points, understanding military pension requirements is key to protecting your financial future.
At USMilitary.com, we are dedicated to helping our service members and veterans get every dollar of the benefits they have earned. From finding the best rates on VA home and personal home loans to navigating VA disability ratings, we serve as your central hub for military life.
Don't leave your hard-earned money on the table. Take the next step in planning your retirement by exploring our comprehensive USMilitary.com Retirement Savings Guide, and make sure you are fully prepared for the road ahead.