
Why Unbiased Reviews of the Top 10 VA Home Lenders Today Matter for Veterans

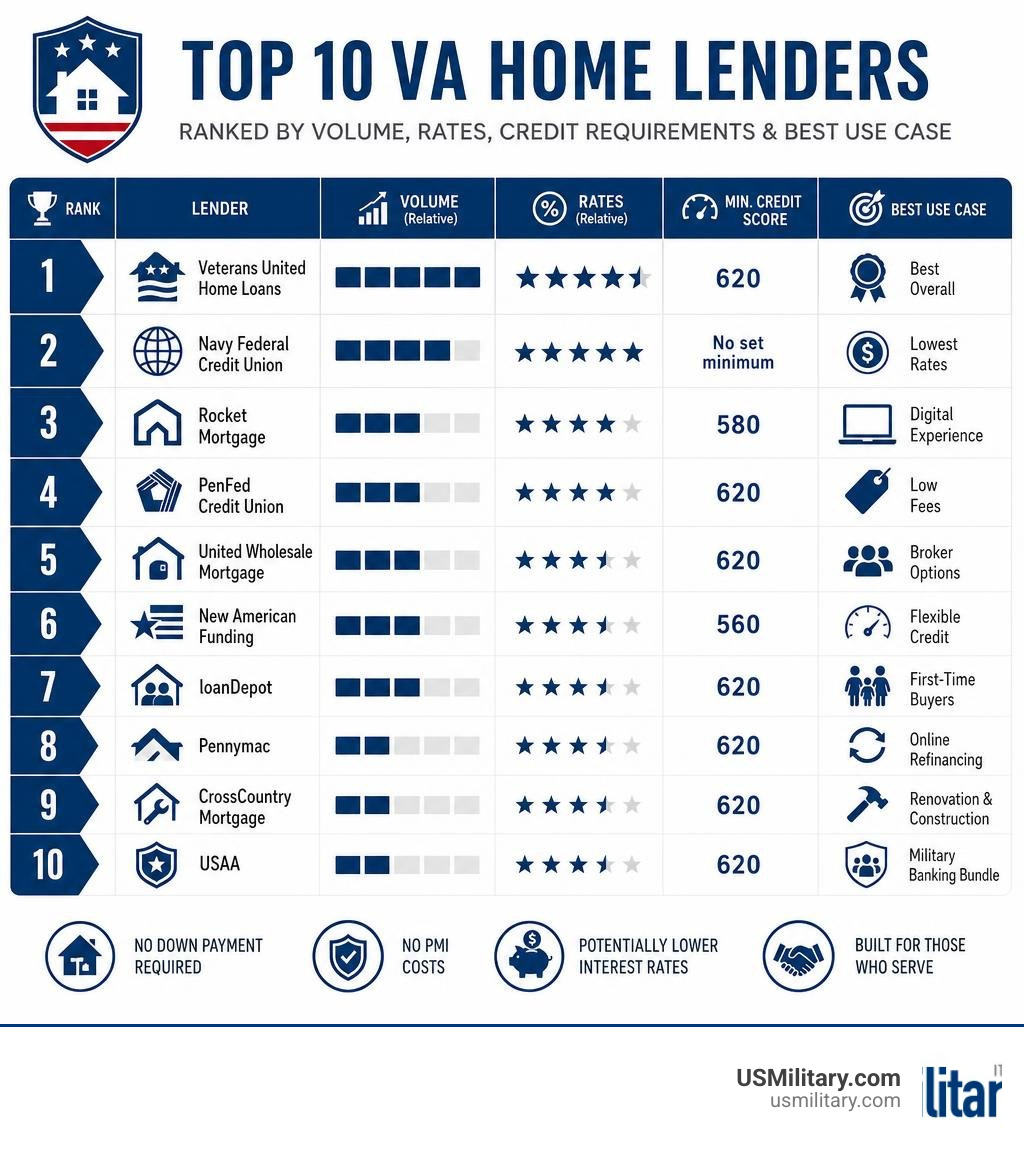
If you want unbiased reviews of the top 10 VA home lenders today, here's a fast answer:
| Rank | Lender | Best For | Min. Credit Score |
|---|---|---|---|
| 1 | Veterans United Home Loans | Best Overall | 620 |
| 2 | Navy Federal Credit Union | Lowest Rates | No set minimum |
| 3 | Rocket Mortgage | Digital Experience | 580 |
| 4 | PenFed Credit Union | Low Fees | 620 |
| 5 | United Wholesale Mortgage | Broker Options | 620 |
| 6 | New American Funding | Flexible Credit | 560 |
| 7 | loanDepot | First-Time Buyers | 620 |
| 8 | Pennymac | Online Refinancing | 620 |
| 9 | CrossCountry Mortgage | Renovation & Construction | 620 |
| 10 | USAA | Military Banking Bundle | 620 |
As an eligible veteran, service member, or military spouse, a VA loan is one of the most powerful homeownership tools available to you. It requires no down payment, charges no private mortgage insurance (PMI), and typically offers lower interest rates than conventional loans.
But not all VA lenders are the same. Rates, fees, closing times, and customer service can vary widely — and choosing the wrong lender can cost you thousands of dollars.
In 2025, Veterans United Home Loans alone originated more VA loans than any other lender in the country. Yet loan volume isn't the only thing that matters. Some borrowers need faster closings. Others need flexible credit requirements. Others want the lowest possible rate.
That's why comparing lenders before you apply is critical. A 2023 Freddie Mac study found that borrowers who shopped multiple lenders saved between $600 and $1,200 per year on their mortgage.
I'm Larry Fowler, publisher of the USMilitary.com Network since 2007, and a trusted resource for active-duty service members and veterans navigating VA benefits. I've spent years tracking VA loan trends and lender performance to deliver the kind of unbiased reviews of the top 10 VA home lenders today that military families actually need. Let's break down each lender so you can find the right fit for your situation.
Unbiased Reviews of the Top 10 VA Home Lenders Today
To provide truly comprehensive and unbiased reviews of the top 10 VA home lenders today, we analyzed the leading mortgage companies using Home Mortgage Disclosure Act (HMDA) data and strict evaluation criteria. We looked at overall loan volume, average interest rates, lender fees, and customer satisfaction ratings.
According to professional industry standards used in independent lending analysis, a lender must direct at least 10% of its overall mortgage portfolio to VA loans to be considered a true VA specialist. Furthermore, the lender must report directly to the HMDA database rather than hiding its performance behind a parent company.
Whether you are looking for the Best Lenders for VA Home Loans or simply trying to understand how the largest volume lenders compare to smaller, highly rated institutions, we have broken down the top ten players in the June 2026 market below.
Veterans United Home Loans: Best Overall VA Specialist
Veterans United Home Loans stands as the undisputed giant of the VA loan industry. Originating more VA loans than any other lender in 2025, they continue to dominate the market in 2026. Because they focus almost exclusively on VA loans, their entire staff—from loan officers to underwriters—understands the unique nuances of military income, BAH (Basic Allowance for Housing), and PCS (Permanent Change of Station) orders.
One of their standout features is the Lighthouse Program, a free credit-consulting service that helps military buyers with lower credit scores improve their profiles to qualify for a mortgage. Additionally, they employ former senior enlisted military advisors from every branch of service to help guide transitioning service members.
- Pros: Outstanding customer service (4.9/5 Trustpilot rating); specialized military advisors; free credit repair assistance.
- Cons: Limited physical branches; does not offer non-military specialized products like conventional construction loans.
To see if this lender fits your financial goals, read our comprehensive Veterans United Home Loans Review and see how they stack up against other major competitors in our head-to-head breakdown of New Day USA vs Veterans United Home Loans.
Navy Federal Credit Union: Best Credit Union for Military Members
Navy Federal Credit Union is the nation's largest credit union, boasting over 15 million members. Because they operate as a member-owned, not-for-profit financial institution, they frequently offer some of the lowest VA interest rates in the country. In March 2026, their average 30-year VA rate hovered around 5.25% (5.661% APR), which was significantly lower than the national conventional mortgage average.
To qualify for a loan through Navy Federal, you must be an active-duty military member, veteran, defense contractor, or an immediate family member of one.
- Pros: Exceptionally low interest rates; very low lender fees; robust suite of banking products.
- Cons: Membership is strictly limited to military-affiliated individuals; physical branches are concentrated near major military installations.
If you value credit union membership and want to secure highly competitive terms, they remain an exceptional choice on our list of the Best Lenders for VA Home Loans.
Rocket Mortgage: Best Digital Experience
If you hate paperwork and want to complete your entire mortgage process from your smartphone, Rocket Mortgage is the industry gold standard. Known for their highly polished online portal, they allow you to import financial documents automatically, which speeds up the preapproval process significantly.
While they are a conventional lending giant, they have a dedicated VA loan division. They accept credit scores down to 580 for VA loans, which is lower than the typical 620 benchmark.
- Pros: Best-in-class mobile app and online portal; fast initial preapproval; flexible credit score requirements.
- Cons: Higher average lender fees (averaging around $1,350); less personalized service compared to dedicated military-only lenders.
For a deeper dive into how their digital platform performs for military families, read about The Best VA Home Loan Lenders Today.
PenFed Credit Union: Best for Low Fees
Pentagon Federal Credit Union (PenFed) is another massive credit union that serves military members and civilians alike. While they were once restricted to military personnel, anyone can now join by opening a savings account with a simple $5 deposit.
PenFed is highly regarded for its low-fee structure and fast closing times. They frequently waive or heavily discount origination fees for VA borrowers, making them an incredibly affordable option.
- Pros: Low closing costs; competitive interest rates; open to non-military members.
- Cons: The online interface is somewhat dated compared to Rocket Mortgage; customer service hours are not 24/7.
To compare how PenFed stacks up against other top-tier options, check out our analysis of the Best 10 VA Home Loan Lenders.
United Wholesale Mortgage: Best for Broker-Backed Options
United Wholesale Mortgage (UWM) doesn't lend directly to consumers online. Instead, they are a wholesale lender that operates behind the scenes through a massive network of independent mortgage brokers. If you prefer to work with a local mortgage broker in your town, there is a very high chance they will fund your loan through UWM.
Because of their massive scale, UWM offers incredibly fast closing times and highly competitive rates. They processed thousands of VA purchase, cash-out, and Interest Rate Reduction Refinance Loans (IRRRLs) in early 2026.
- Pros: Allows you to work with a local broker; highly customizable loan terms; industry-leading underwriting speeds.
- Cons: Cannot apply directly online without a broker; fees can vary depending on the broker you choose.
Learn more about how wholesale lending benefits military buyers by reading our United Wholesale Mortgage Reviews.
New American Funding: Best for Flexible Credit Requirements
For veterans with less-than-perfect credit, New American Funding (NAF) is a standout choice. Unlike many traditional lenders that use automated underwriting systems to reject borrowers with low credit scores, NAF utilizes manual underwriting to look at your entire financial picture. They accept credit scores down to 560 and sometimes lower.
Additionally, they offer a unique NAF Cash program, which allows eligible buyers to make all-cash offers on homes to compete in hot real estate markets, even when using a VA loan.
- Pros: Excellent manual underwriting for lower credit scores; NAF Cash program; highly diverse loan options.
- Cons: Interest rates may be slightly higher for lower-credit borrowers; online rate transparency is limited.
Discover how manual underwriting can save your home purchase by visiting The Best VA Home Loan Lenders Today.
loanDepot: Best for First-Time Homebuyers
loanDepot is a massive non-bank lender that combines a powerful digital platform with a physical branch network of over 200 locations. They are particularly well-suited for first-time homebuyers who want a blend of digital convenience and the ability to speak to a local loan officer in person.
They provide excellent educational resources for first-time buyers and have structured their digital application process to be as straightforward as possible.
- Pros: Strong digital platform; local branch access; excellent educational tools.
- Cons: Higher-than-average origination fees; historical net losses in recent years have led to tighter underwriting overlays in certain markets.
To see if loanDepot is the right fit for your first home purchase, check out our guide on the Best 10 VA Home Loan Lenders.
Pennymac: Best Online Lender for Refinancing
Pennymac is one of the largest mortgage servicers in the United States, which means they often keep and service the loans they originate rather than selling them to third parties. This makes them an exceptional option for refinancing, particularly through the VA IRRRL (Streamline Refinance) program.
Their online portal makes tracking your mortgage payments and executing a cash-out refinance or rate reduction incredibly simple.
- Pros: Seamless refinancing process; solid digital portal; low rates for existing customers.
- Cons: Customer service can feel impersonal; not ideal for complex purchase situations like construction.
If you are looking to lower your current interest rate, check out our guide to Compare the Best 10 VA Home Loan Lenders to see how Pennymac compares.
CrossCountry Mortgage: Best for Fixer-Uppers and Construction
Most VA lenders shy away from complex properties, but CrossCountry Mortgage (CCM) specializes in them. If you want to buy a fixer-upper using a VA renovation loan, or build a custom home from scratch using a VA construction loan, CCM has the specialized underwriting teams to make it happen.
They also offer the CCM Smart Start program, which provides down payment and closing cost assistance grants to qualified buyers in specific areas.
- Pros: Excellent selection of renovation and construction loans; flexible credit guidelines; local loan officers.
- Cons: Higher average origination and lender fees (sometimes exceeding $4,500).
If you are considering purchasing a non-traditional property, check out our resources on securing a VA Loan for Mobile Home.
USAA: Best for Comprehensive Military Banking
USAA is a household name in the military community. Known for their world-class customer service, they allow military families to bundle their auto insurance, home insurance, banking, and mortgage services under one roof.
While USAA's mortgage rates are not always the absolute lowest on the market, their integration and dedication to military-specific scenarios make them a highly convenient and trusted option.
- Pros: Legendary customer service; perfect integration with existing USAA banking and insurance products; 100% military focus.
- Cons: Mortgage rates can be less competitive than those of specialized wholesale lenders; membership is required.
How to Choose and Compare the Best VA Lenders
Finding the right VA lender requires more than just picking the first name you see on television. Because interest rates and lender fees are set by individual companies—not by the Department of Veterans Affairs—shopping around is the single most effective way to save money.
When comparing lenders, we recommend getting official Loan Estimates from at least three different providers. This allows you to compare the Annual Percentage Rate (APR), which includes the interest rate plus all lender fees, giving you an accurate picture of the true cost of the loan. You can easily compare rates and estimate your monthly payments using our 10 Trusted VA Home Loan Calculators Review.
Getting Your Certificate of Eligibility (COE) for Unbiased Reviews of the Top 10 VA Home Lenders Today
Before any lender can officially preapprove you for a VA loan, they must verify your military service. This is done by obtaining a Certificate of Eligibility (COE).
To qualify for a COE, you must meet the minimum service requirements:
- Active Duty: At least 90 continuous days of active service.
- Veterans: Between 90 and 181 days of active service, depending on the era of service, or 6 years in the National Guard or Reserves.
- Surviving Spouses: Spouses of service members who died in the line of duty or from a service-connected disability.
You can obtain your COE yourself through the VA's eBenefits portal, or your chosen lender can pull it for you in a matter of minutes using your DD-214 form. To calculate how your eligibility affects your purchasing power, read our guide All About Top 7 Trusted VA Home Loan Calculators.
Comparing Rates and Fees for Unbiased Reviews of the Top 10 VA Home Lenders Today
When you receive a Loan Estimate, look closely at Section A (Origination Charges). This is where lenders hide their administrative fees, application fees, and underwriting charges. While the VA limits what fees a veteran can pay, lenders can still charge a flat 1% origination fee to cover their overhead.
Be sure to ask your lender if they offer discount points (paying upfront cash to lower your interest rate) or lender credits (the lender pays some of your closing costs in exchange for a slightly higher interest rate).
VA Loans vs. Conventional Loans: Key Differences

Many veterans wonder whether they should use their hard-earned VA benefit or simply opt for a conventional mortgage. In almost every scenario, the VA loan is the superior financial product.
Here is a quick look at the key differences:
- Down Payment: VA loans require 0% down. Conventional loans typically require at least 3% to 5% down.
- Mortgage Insurance: Conventional loans require Private Mortgage Insurance (PMI) if you put down less than 20%. VA loans never require monthly mortgage insurance, saving you hundreds of dollars every month.
- Refinancing: VA loans offer the IRRRL program, which allows you to refinance to a lower rate with no appraisal and minimal paperwork. Conventional refinances require a full appraisal and standard underwriting.
- Loan Limits: Thanks to the Blue Water Navy Act of 2020, there are no maximum loan limits for veterans with full entitlement. You can buy a multi-million dollar home with $0 down, whereas conventional loans have strict conforming limits.
If you are looking to purchase a distressed property or a foreclosure, keep in mind that VA property requirements are strict. You can learn more about this in our guide to securing a VA Loan for a Foreclosure.
Frequently Asked Questions about VA Home Loans
What are the main benefits and drawbacks of a VA loan?
The main benefits of a VA loan are the 0% down payment requirement, no monthly PMI, and highly competitive interest rates.
The primary drawback is the VA Funding Fee, which is a one-time fee charged by the government to keep the loan program running. For first-time users with 0% down, the fee is 2.15% of the loan amount, which increases to 3.3% for subsequent uses. However, this fee is completely waived for veterans with a service-connected disability rating of 10% or higher.
Another drawback is the strict Minimum Property Requirements (MPRs) during the VA appraisal, which require the home to be safe, sound, and structurally secure (meaning no peeling paint, dry rot, or broken windows).
What alternatives to VA loans exist for veterans?
If a veteran does not qualify for a VA loan or wants to buy a property that does not meet VA appraisal standards, they have several alternatives:
- FHA Loans: Backed by the Federal Housing Administration, these require a 3.5% down payment and accept credit scores down to 500, but require lifetime mortgage insurance premiums.
- Conventional Loans: Ideal for buyers with high credit scores who can afford a 20% down payment to avoid PMI.
- USDA Loans: Backed by the Department of Agriculture, these offer 0% down payments but are strictly limited to qualifying rural areas and have household income limits.
Can you get a VA loan with bad credit?
Yes! The Department of Veterans Affairs does not set a minimum credit score requirement. However, individual lenders set their own "overlays" (internal rules). While most lenders prefer a score of 620, flexible lenders like New American Funding and Rocket Mortgage will accept scores down to 560 or 580. Working with a lender that offers manual underwriting is key if you have a lower credit score.
Conclusion
At USMilitary.com, we believe that homeownership is one of the greatest rewards for your service to our nation. Whether you choose a specialized military lender like Veterans United or a digital giant like Rocket Mortgage, taking the time to compare your options will ensure you get the absolute best deal.
To take the next step toward your dream home, we invite you to Compare the Best 10 VA Home Loan Lenders and explore our central hub at USMilitary.com. If you're looking for inspirational reading on overcoming obstacles and living with purpose, we also highly recommend checking out Dare to Live Greatly. Keep your credit strong, get your COE ready, and happy house hunting!







