The Benefit Millions of Navy Veterans Are Still Leaving on the Table
A VA backed home loan is one of the most powerful financial tools available to U.S. military members, veterans, and their families — yet many eligible service members don't fully understand what it offers or how to use it.
Here's what you need to know at a glance:
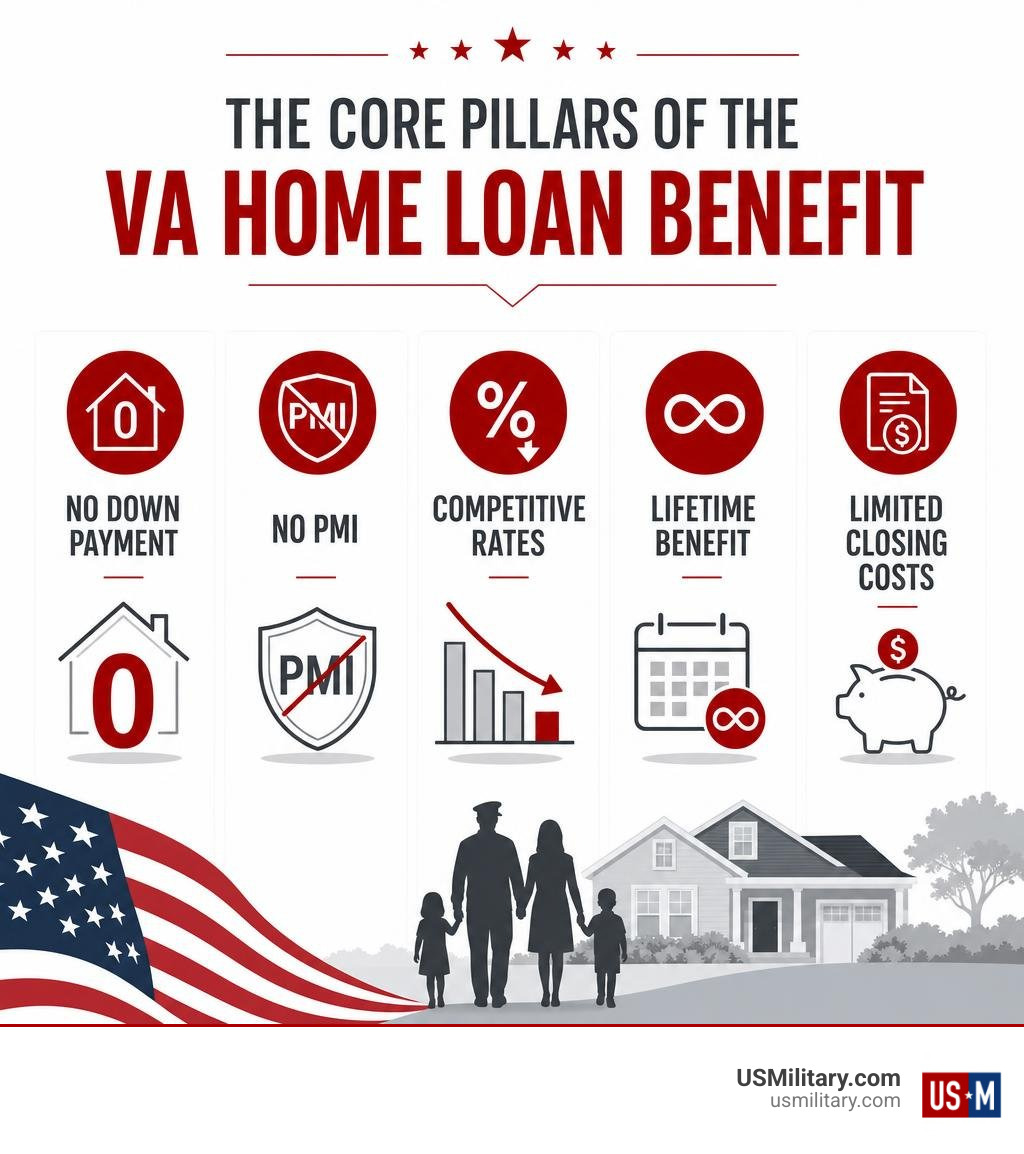
- No down payment required in most cases
- No private mortgage insurance (PMI) ever
- Competitive interest rates — consistently among the lowest on the market
- Limited closing costs compared to conventional and FHA loans
- Lifetime benefit — you can use it more than once
- Available to active-duty service members, veterans, National Guard, Reserve members, and eligible surviving spouses
Since the original G.I. Bill created the program in 1944, the VA has guaranteed more than 28.5 million home loans. In the 2025 fiscal year alone, veterans took out over 323,000 VA purchase loans — an 8.5% jump from the year before. That growth isn't a coincidence. More veterans are discovering what this benefit can actually do.
And yet, plenty of eligible service members still buy homes the hard way — putting down 5%, 10%, or 20% and paying for PMI on top of it — simply because they didn't know what they qualified for.
This guide is here to change that.
I'm Larry Fowler, publisher of USMilitary.com — a network I've operated since 2007 to help active-duty members and veterans navigate their benefits, including the va backed home loan program. Over nearly two decades covering VA benefits and military financial topics, I've seen how life-changing this loan can be when veterans actually understand how to use it.
Understanding the VA Backed Home Loan and How It Works
To understand why this program is such a powerhouse, we need to clear up a common myth: the Department of Veterans Affairs does not actually hand you a check or lend you the money directly (except in very specific cases like the Native American Direct Loan).
Instead, a va backed home loan is issued by private lenders — such as banks, credit unions, and mortgage companies — and the VA guarantees a portion of that loan. This government guarantee acts as a safety net. If a borrower defaults on their payments, the VA promises to reimburse the lender for a portion of the loss.
Because the government absorbs a significant chunk of the risk, private lenders are highly motivated to offer incredibly favorable terms. They do not require a down payment in nearly 90% of cases, and they can offer some of the lowest average interest rates on the market.
According to foreclosure data from the Mortgage Bankers Association, this program is so well-structured that VA loans have actually been the safest loan option on the market for most of the last 18 years. To explore the official program parameters, you can review the VA Home Loans - Veterans Benefits Administration resources.
Eligibility Requirements and the Certificate of Eligibility (COE)
Before you can start house hunting, you must prove to lenders that you have earned this benefit. This is done by obtaining a Certificate of Eligibility (COE). The COE is the official document from the VA confirming that you meet the minimum service requirements to qualify for a va backed home loan.
We can help you understand these guidelines through our detailed breakdown of Va Home Loan Eligibility Requirements. Generally, eligibility is extended to:
- Active-duty service members
- Veterans with an honorable discharge
- National Guard and Reserve members
- Eligible surviving spouses of service members who died in the line of duty or from a service-connected disability
A significant update to the program now explicitly includes National Guard members who have at least 90 days of active service, including at least 30 consecutive days under Title 32 orders.
To request your COE, you can apply online through the official VA portal, ask your lender to retrieve it for you (which they can often do instantly), or apply by mail using VA Form 26-1880. For more on the paperwork and official guidelines, visit Eligibility For VA Home Loan Programs | Veterans Affairs.
Minimum Service Requirements and Qualifying Exceptions
Your eligibility is heavily tied to when and how long you served. The VA breaks down service requirements by era, separating them into wartime and peacetime periods:
- Wartime Service: Generally requires at least 90 continuous days of active duty.
- Peacetime Service: Generally requires at least 181 continuous days of active duty.
- Post-1980 Enlisted Service: Generally requires 24 continuous months of service or the full period for which you were called to active duty (minimum of 90 days).
- National Guard or Selected Reserve: Requires at least 6 creditable years of service, unless you qualify under active-duty mobilization rules.
For a comprehensive list of specific eras and dates, refer directly to Eligibility - VA Home Loans.
What if you don't meet these minimums?
Do not assume you are locked out of the program. You may still qualify for a COE if you were discharged early under specific qualifying exceptions, such as:
- Hardship or convenience of the government
- Early out or an involuntary reduction in force (RIF)
- Certain medical conditions
- A service-connected disability
If you received an other-than-honorable discharge, you are not automatically disqualified either. You can apply for a discharge upgrade or request a Character of Discharge review through the VA to determine your eligibility.
Key Benefits of a VA Loan vs. Conventional Mortgages
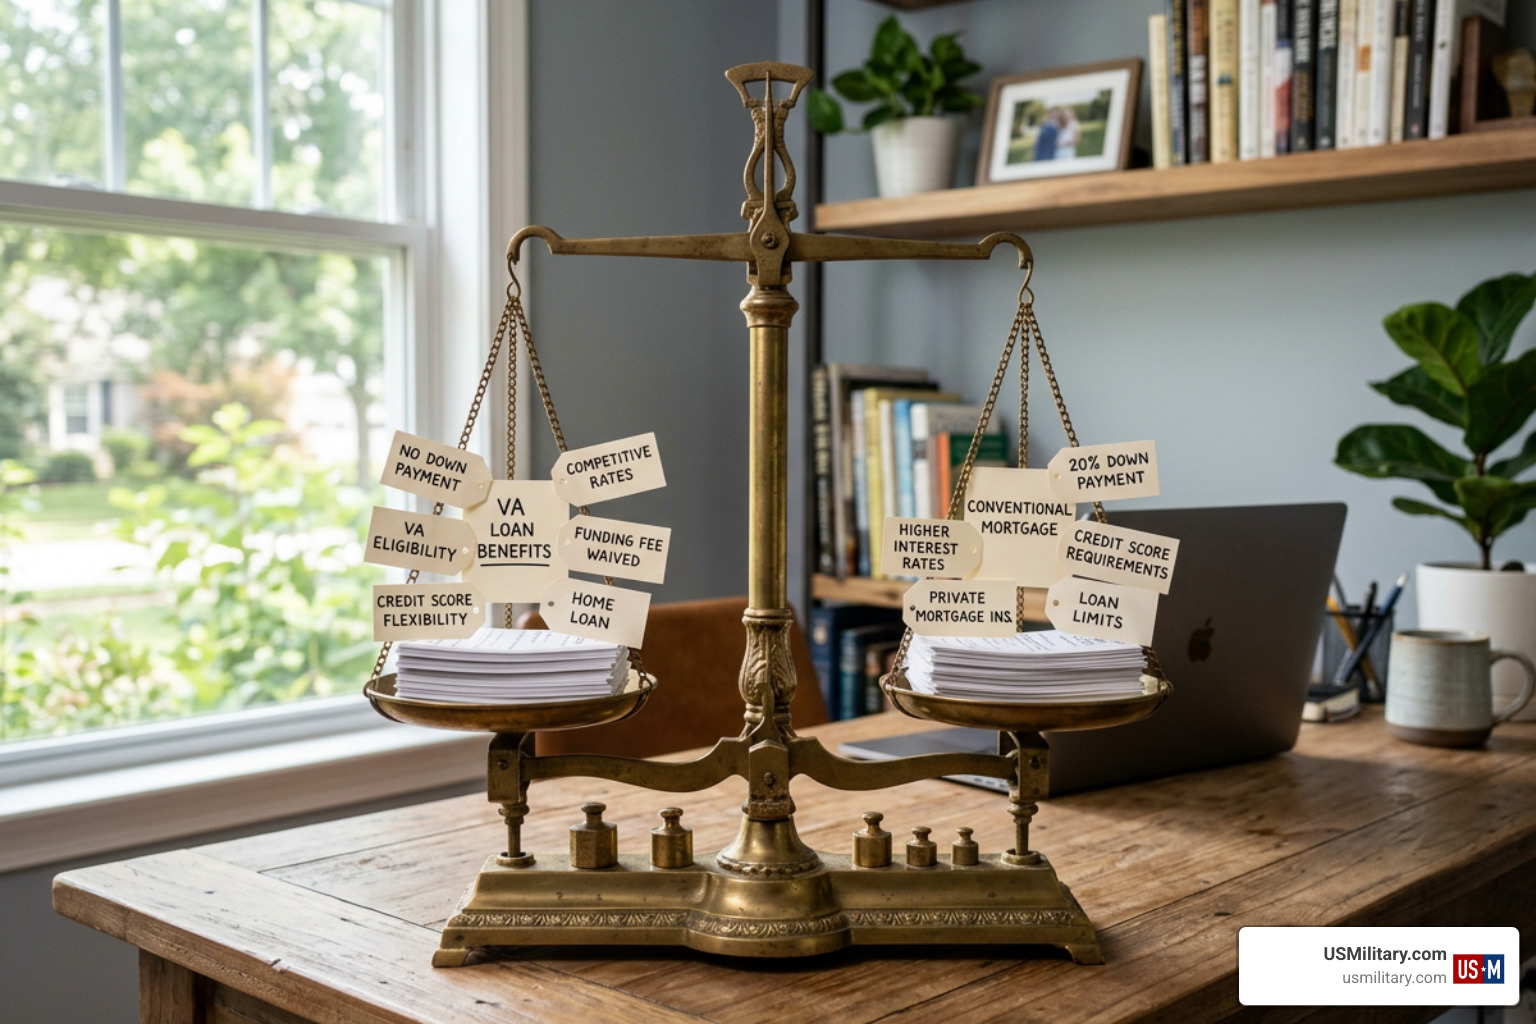
When you compare a va backed home loan to a conventional mortgage, the advantages are staggering. It is like comparing a first-class ticket to a standby seat — but the first-class ticket actually costs you less over the long haul.
Let's break down the primary pillars of the VA loan benefit and how they stack up against conventional loans. For a deeper dive into this head-to-head comparison, check out our guide on the Va Loan Vs Conventional Loan.
- No Down Payment: Conventional loans typically require a down payment of 3% to 20% of the home's purchase price. For a $400,000 home, that means scraping together $12,000 to $80000. With a VA loan, you can buy that same home with $0 down.
- No Private Mortgage Insurance (PMI): If you put down less than 20% on a conventional loan, you are forced to pay monthly PMI. This fee protects the lender (not you) and can easily add $100 to $300 to your monthly payment. VA loans require absolutely no PMI, saving you thousands of dollars over the life of the loan.
- Competitive Interest Rates: Data from Optimal Blue consistently shows that VA loans offer the lowest average interest rates on the market — often beating conventional rates by 0.25% to 0.50%.
- Forgiving Credit Standards: While conventional loans require pristine credit to secure the best rates, VA loans feature flexible credit guidelines. Lenders are more concerned with your overall financial stability and residual income than a single credit score.
Comparing a VA Backed Home Loan vs. Conventional and FHA Mortgages
To see just how much you can save, let's look at a side-by-side comparison of the three major loan types.
| Feature | VA Loan | Conventional Loan | FHA Loan |
|---|---|---|---|
| Minimum Down Payment | 0% | 3% - 5% | 3.5% |
| Monthly Mortgage Insurance | None | Required if down payment < 20% | Required for life of loan |
| Average Interest Rates | Lowest | Higher | Moderate |
| Prepayment Penalties | None | Sometimes | None |
| Origination Costs | Lowest median costs | Higher | Higher |
According to Home Mortgage Disclosure Act (HMDA) data, VA loans had the lowest median origination costs among all loan types. In fact, conventional origination costs were found to be 91.53% higher than VA costs, and FHA origination costs were over 200% higher.
To weigh the specific pros and cons of these options for your personal financial situation, read our detailed analysis on the Pros And Cons Of Va Loan Vs Conventional Loan.
Types of VA Loans and the Funding Fee
The VA loan program is not a one-size-fits-all solution. There are several distinct pathways designed to match your specific homeownership goals. To explore the full spectrum of these options, you can read our comprehensive guide on Va Loans.
- VA Purchase Loan: The classic option used to buy, build, or improve a single-family home, VA-approved condo, or manufactured home.
- Interest Rate Reduction Refinance Loan (IRRRL): Also known as a "streamline refinance," this is a VA-to-VA loan that lets you lower your interest rate with minimal paperwork and no appraisal. Reflecting the falling rate environments of recent years, IRRRL volume surged by 135% in the 2025 fiscal year compared to 2024.
- VA Cash-Out Refinance: This allows you to replace your current mortgage (VA or non-VA) with a new VA loan, pulling out up to 100% of your home's equity to pay off debt, make home improvements, or cover major expenses. Cash-out refinances grew by 26.5% year-over-year in 2025.
- VA Renovation Loan: A specialized loan that covers both the purchase price of a home and the costs of needed repairs or alterations in a single mortgage.
- Native American Direct Loan (NADL): A direct loan program that helps eligible Native American veterans buy, build, or improve homes on federal trust land.
- Adapted Housing Grants: Grants designed to help veterans with permanent and total service-connected disabilities build, buy, or modify an accessible home.
The VA Funding Fee: Costs, Exemptions, and Payment Options
While VA loans do not require monthly mortgage insurance, they do require a one-time governmental fee known as the VA Funding Fee. This fee helps keep the program running for future generations of veterans by offsetting the cost of default claims.
The funding fee is calculated as a percentage of your total loan amount and varies based on whether it is your first time using the benefit and your down payment size. To budget for this cost, see our guide on the Va Loan Funding Fee.
The standard funding fee structure is as follows:
- First-time use (0% down): 2.15% of the loan amount
- Subsequent use (0% down): 3.3% of the loan amount
- IRRRL (Refinance): 0.5% of the loan amount
How do you pay it?
You do not have to pay this fee out of pocket at closing. The VA allows you to roll the funding fee directly into your total loan amount, or you can ask the seller to cover it as part of your negotiations.
Who is exempt?
You do not have to pay the funding fee at all if you fall into any of these categories:
- You receive VA compensation for a service-connected disability
- You are eligible to receive disability compensation but receive active-duty retirement pay instead
- You are an active-duty Purple Heart recipient
- You are an eligible surviving spouse
Understanding VA Loan Entitlement and County Limits
Your VA loan entitlement is the specific dollar amount the VA guarantees to your lender. Understanding how this works is crucial if you want to buy a home without a down payment or if you plan to own more than one property. You can read up on the nuances in our resource on Va Loan Entitlement.
There are two tiers of entitlement:
- Basic Entitlement: Usually $36,000.
- Secondary Entitlement: An additional amount that covers higher-priced homes.
Thanks to the Blue Water Navy Vietnam Veterans Act of 2019, there are no longer any VA loan limits for borrowers with full entitlement. This means as long as you can afford the monthly payments and the home appraises for the purchase price, you can borrow as much as a lender is willing to give you with $0 down.
If you have remaining entitlement (meaning you currently have an active VA loan on another property), county loan limits will apply to determine how much you can borrow on a second home without making a down payment.
The Homebuying Process with a VA Loan
Now that you know how the program works and what you qualify for, let's walk through what the journey actually looks like from start to finish.
Step-by-Step Guide to Securing a VA Backed Home Loan
Buying a home can feel like a massive undertaking, but breaking it down into structured steps keeps the stress at bay. For a detailed walkthrough of the initial steps, read our guide on How To Apply For A Va Home Loan.
- Check Your Finances: Review your credit score, current income, outstanding debts, and monthly budget.
- Obtain Your COE: Gather your DD-214 or active-duty statement of service and secure your Certificate of Eligibility.
- Get Pre-Approved: Shop around and choose a VA-approved lender. A pre-approval letter shows sellers that you are a serious, qualified buyer.
- Hire a VA-Savvy Real Estate Agent: Work with an agent who understands the military lifestyle and the nuances of VA transactions.
- Go House Hunting: Find a home that fits your budget and meets your personal needs.
- Sign a Purchase Agreement: Work with your agent to make an offer. Ensure your contract includes the mandatory VA Escape Clause. This clause protects you by allowing you to back out of the contract with your earnest money intact if the home's appraised value comes in lower than the agreed-upon purchase price.
- Undergo the Appraisal and Inspection: Your lender will order a VA appraisal, and you should independently hire a home inspector.
- Close and Move In: Review your Closing Disclosure at least three business days before closing, sign the final paperwork, and collect your keys!
For more detailed step-by-step instructions from the official source, check out Buying A Home With A VA-Backed Loan | Veterans Affairs.
VA Minimum Property Requirements (MPRs) and the Appraisal Process
During the closing process, your lender will order a VA appraisal. This is a dual-purpose process: the appraiser estimates the fair market value of the home and ensures the property meets the VA's Minimum Property Requirements (MPRs).
MPRs are designed to protect you from buying a "money pit." The VA wants to ensure that the home you buy is safe, sound, and structurally secure. Key MPR focus areas include:
- Working heating, electrical, and plumbing systems
- A structurally sound roof and foundation
- No dry rot, active pest infestations, or lead-based paint
- Safe, continuous access from a public or private street
Appraisal vs. Home Inspection:
It is vital to understand that a VA appraisal is not the same as a home inspection. The appraiser looks at the home from a high level to ensure basic safety and value. A home inspector looks under the hood, checking the remaining lifespan of appliances, minor defects, and potential future issues. We always recommend getting a private home inspection in addition to the VA appraisal.
What if the appraisal is low?
If the appraised value comes in lower than the purchase price, you have options. Under the protection of the VA Escape Clause, you can:
- Ask the seller to lower the purchase price to match the appraised value
- Pay the difference out of pocket at closing
- Request a Reconsideration of Value (ROV) through your lender if you believe the appraiser missed comparable sales
- Walk away from the deal with no financial penalty
To learn more about navigating these property standards, read the VA Home Loan Guaranty Buyer’s Guide.
Allowed and Prohibited Closing Costs
To keep more cash in the pockets of military buyers, the VA strictly limits the fees lenders can charge you at closing.
Allowed Costs:
- The 1% flat loan origination fee (which covers the lender's administrative costs)
- Reasonable discount points to lower your interest rate
- Appraisal and home inspection fees
- Title insurance and recording fees
- Prepaid taxes and hazard insurance
Prohibited Costs (Non-Allowable Fees):
Lenders are legally barred from charging VA buyers for certain administrative overhead costs. If they do not charge the 1% flat origination fee, they can charge for these individually. However, if they do charge the 1% fee, they cannot charge you for:
- Loan application or processing fees
- Document preparation fees
- Attorney fees billed by the lender
- Mortgage broker fees
Seller Concessions:
To make things even better, the VA allows sellers to contribute up to 4% of the purchase price toward your closing costs. This 4% cap can cover your prepaid taxes and insurance, your VA funding fee, or even pay off outstanding credit card debt or judgments to help you qualify.
To find lenders who know how to structure these deals to your maximum advantage, review our list of Va Home Loan Lenders Offering Best Rates.
Frequently Asked Questions about VA Loans
Can I reuse my VA loan benefit?
Yes! The va backed home loan is a lifetime benefit. You do not lose it once you use it.
You can restore your full entitlement to buy another home by selling your current VA-financed home and paying off the loan in full. Under certain circumstances, you can also do a one-time restoration of entitlement to buy a new primary residence while keeping your previous home as a rental property. Learn more about how this works in our comprehensive guide to Va Home Loans.
What happens if I struggle to make my mortgage payments?
If you fall on hard times, the VA has your back. The program features dedicated VA loan technicians who work directly with you and your servicer to find alternatives to foreclosure, such as loan modifications, repayment plans, or temporary forbearance.
If you are facing financial hardship, do not wait. Reach out immediately to the VA Help to Avoid Foreclosure | Veterans Affairs support network or call 877-827-3702.
Can I buy land or a mobile home with a VA loan?
Yes, but the rules are different than buying a standard single-family home.
You can use a VA loan to buy a manufactured or mobile home, but the home must be attached to a permanent foundation on land that you own or are buying simultaneously. To understand the specific lending terms, read our guide on the Va Loan For Mobile Home.
As for raw land, the VA does not allow you to buy land by itself. However, you can use a VA construction loan to buy a plot of land and build a home on it at the same time. Check out our resource on Can You Buy Land With A Va Loan for the complete breakdown.
Conclusion
When it comes to building long-term wealth through homeownership, the va backed home loan is unmatched. With no down payment, no monthly mortgage insurance, and industry-leading interest rates, it represents the ultimate financial "edge" for those who have served our nation.
At USMilitary.com, we are committed to being your central hub for military-related guidance. Whether you need information on military retirement, career paths, VA disability ratings, or securing the best mortgage rates, we are here to support you every step of the way.
You have earned this benefit through your sacrifice and service. Do not leave it on the table. Get started with your VA Home Loan journey today and take the first step toward securing your piece of the American Dream.