What VA Military Benefits For Navy SEAL Spouses Actually Cover
VA military benefits for Navy SEAL spouses include a broad set of federal programs that most families never fully use — because no one walked them through the options.
Here's a quick overview of the major benefits available:
| Benefit | Who It's For | Key Detail |
|---|---|---|
| CHAMPVA Healthcare | Spouse of 100% P&T or TDIU veteran | No monthly premium; cost-sharing applies |
| Dependency and Indemnity Compensation (DIC) | Surviving spouse of service-connected death | $1,699.36/month tax-free in 2026 |
| DEA / Chapter 35 Education | Spouse of 100% P&T or deceased veteran | Up to 36 months of education benefits |
| GI Bill Transfer of Entitlement | Spouse of active-duty service member | Must be transferred before separation |
| PCAFC Caregiver Stipend | Spouse providing daily care to disabled veteran | Level 1 or Level 2 monthly stipend |
| VA Home Loan Guaranty | Surviving spouse (unremarried or remarried after 57) | No down payment required in most cases |
| Survivors Pension | Low-income surviving spouse of wartime veteran | Means-tested; 2026 net worth limit $163,699 |
| Survivor Benefit Plan (SBP) | Surviving spouse enrolled before veteran's death | Now fully concurrent with DIC since 2023 |
Being married to a Navy SEAL means living with unique pressures — long and classified deployments, a higher physical toll from special operations service, and a transition process that often leaves spouses scrambling for answers on their own.
The good news: these benefits are real, substantial, and accessible. The challenge is knowing where to start and how to apply correctly.
I'm Larry Fowler, publisher of USMilitary.com and a longtime resource for veterans and military families navigating VA military benefits for Navy SEAL spouses and beyond. Since 2007, I've helped hundreds of thousands of active-duty members and veterans understand their VA benefits, disability ratings, and survivor programs. In this guide, I'll walk you through every major program available to Navy SEAL spouses — so you don't leave a dollar of earned support on the table.
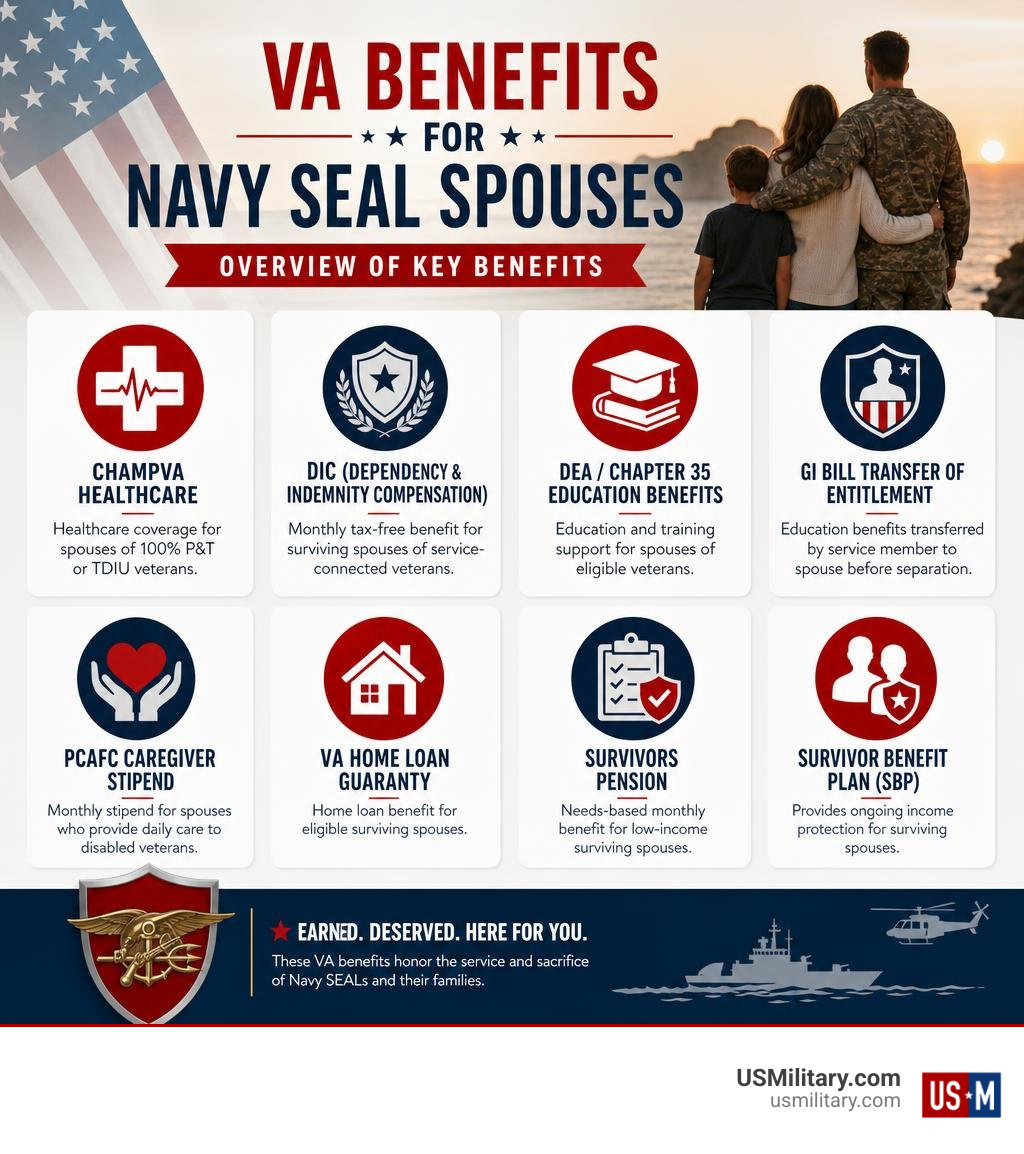
Simple guide to VA Military Benefits For Navy SEAL Spouses:
- VA Veteran Benefits
- Maximizing 100 Percent Disabled Veteran Benefits
- Will The VA Cover The In Home Care Costs For Wartime Veterans
VA Military Benefits For Navy SEAL Spouses: Core Programs Explained
When we look at the spectrum of military spouse benefits, the sheer volume of acronyms can make your head spin. But before diving into the complex medical and educational programs, we have to start with the absolute fundamentals.
To access any federal or military benefit, a Navy SEAL spouse must first be registered in the Defense Enrollment Eligibility Reporting System (DEERS) and obtain a valid military ID card. Without this crucial step, the gateway to healthcare, base privileges, and educational transfers remains locked.
For families navigating life with a veteran who has returned with physical or psychological wounds, the VA offers specialized support pathways. If your spouse has sustained severe service-connected injuries, we highly recommend reading our guide on Spouse Benefits for Disabled Veterans to understand how disability ratings dictate your family's financial security.
When a veteran receives a 100% permanent and total (P&T) rating, the level of support changes dramatically. Spouses of these veterans gain access to premier healthcare, monthly stipends, and educational grants. You can learn more about these specific milestones in our 100 Percent Disabled Veteran Benefits for Spouses Key Guide.
Navigating CHAMPVA Healthcare: VA Military Benefits For Navy SEAL Spouses
One of the most valuable yet frequently misunderstood health benefits is the Civilian Health and Medical Program of the Department of Veterans Affairs (CHAMPVA). This is a comprehensive, cost-sharing program designed specifically for the spouses and dependents of veterans who meet very strict criteria.
To qualify for CHAMPVA, the Navy SEAL veteran must meet one of the following conditions:
- Be rated 100% permanently and totally disabled due to a service-connected condition.
- Be rated for Individual Unemployability (TDIU) due to service-connected disabilities.
- Be the surviving spouse of a veteran who died from a service-connected disability or was 100% P&T at the time of death.
It is important to understand the transition from active-duty healthcare to veteran healthcare. While your spouse is on active duty, you are covered by TRICARE. Once the veteran separates with a 100% P&T rating, you transition to CHAMPVA.
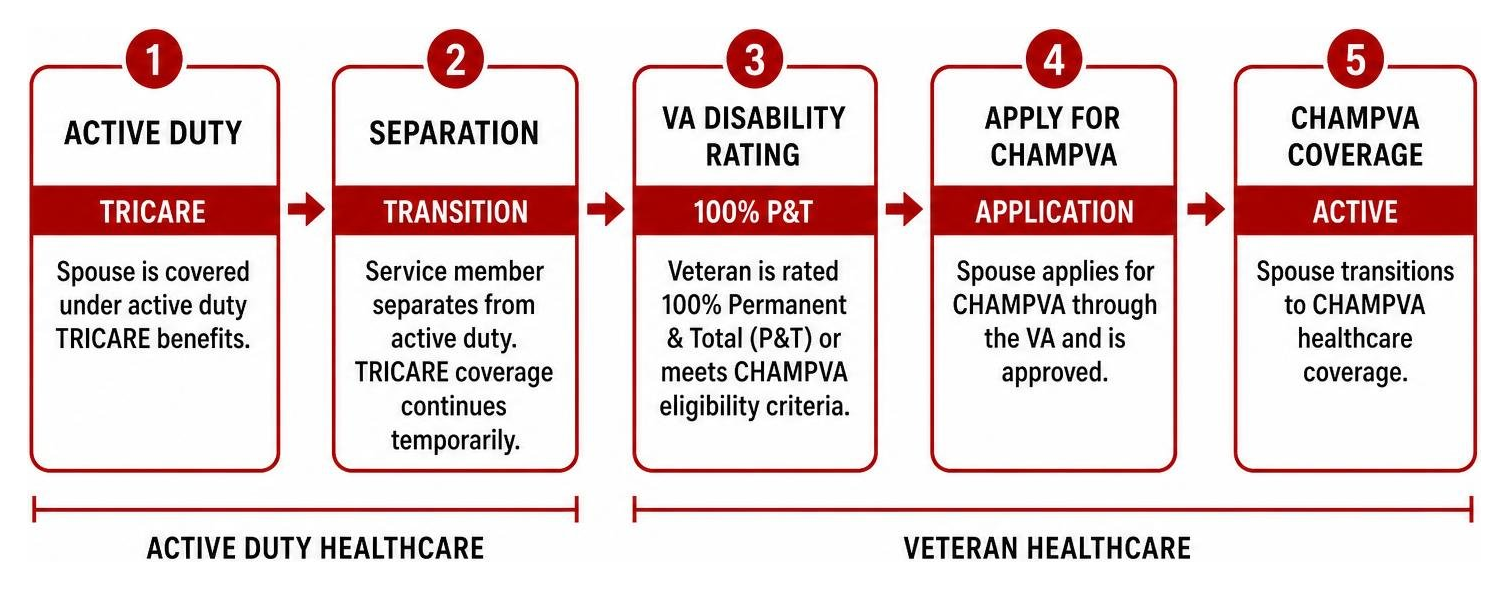
To help visualize how CHAMPVA differs from the standard TRICARE Select program, we have broken down the core differences:
| Feature | TRICARE Select | CHAMPVA |
|---|---|---|
| Administering Agency | Department of Defense (DoD) | Department of Veterans Affairs (VA) |
| Eligibility | Active duty, retirees, and their families | Spouses/dependents of 100% P&T or deceased veterans |
| Monthly Premiums | Yes (for retirees/families) | None |
| Out-of-Pocket Costs | Deductibles and copays apply | 25% cost-share up to a $3,000 annual cap |
| Medicare Coordination | Becomes secondary to Medicare at 65 | Requires Medicare Part A & B to maintain coverage at 65 |
CHAMPVA covers standard medical services, prescription medications (including the convenient Meds by Mail program), mental health services, and preventive care. That if you are age 65 or older, you must be enrolled in Medicare Part A and Part B to keep your CHAMPVA eligibility. To explore more about health coverage and specialized care pathways, check out the Disabled Veteran Spouse Benefits: Complete 2026 Guide.
Education and Career Assistance: VA Military Benefits For Navy SEAL Spouses
If you are looking to advance your career or complete a degree, the VA provides exceptional educational resources. The primary program for spouses is the Survivors' and Dependents' Educational Assistance (DEA) program, also known as Chapter 35.
DEA provides up to 36 months of tax-free monthly educational benefits directly to the spouse to cover college tuition, vocational training, or apprenticeship costs. For qualifying events occurring after August 1, 2023, the VA has removed the previous time limits, meaning you can use these benefits at any point in your life without worrying about an expiration date.
Additionally, active-duty spouses can utilize the My Career Advancement Account (MyCAA) scholarship program, which provides up to $4,000 in tuition assistance for licenses, certifications, or associate degrees in high-demand career fields. For a deeper dive into how these educational programs function alongside other family support structures, read the official guide on Transferred Education Benefits For Family Members.
GI Bill Transfer of Entitlement Rules
Another powerful educational tool is the transfer of Post-9/11 GI Bill benefits. An active-duty Navy SEAL can choose to transfer some or all of their unused GI Bill months to their spouse.
However, there is a catch: this transfer must be initiated and approved while the service member is still on active duty or serving in the Selected Reserve. Once the veteran separates or retires, they can no longer transfer unused GI Bill benefits to a spouse.
The service member must have completed at least six years of service and agree to serve an additional four years to execute the Transfer of Education Benefits (TEB) through the milConnect portal. Spouses can use these transferred benefits immediately while the member is on active duty.
Navigating the educational and emotional shifts of special operations life requires unique resilience, as explored in our profiles on the Navy SEAL Wife experience.
Survivor Benefits: DIC, Pensions, and the Elimination of the Widows Tax

Losing a spouse who served in the special operations community is a devastating experience. During such times, understanding how benefits transition from living-veteran programs to survivor programs is critical for maintaining financial stability. We must ensure that Gold Star and surviving spouses know exactly what they are entitled to receive.
To understand the broader financial framework of VA compensation and how these numbers are calculated, you can refer to our VA Disability Pay 2026 Guide.
Dependency and Indemnity Compensation (DIC) 2026 Rates
Dependency and Indemnity Compensation (DIC) is a tax-free monthly monetary benefit paid to eligible surviving spouses of military service members who died in the line of duty, or veterans whose death resulted from a service-connected injury or illness.
For 2026, the base monthly DIC rate for surviving spouses is $1,699.36. This rate reflects a 2.8% Cost-of-Living Adjustment (COLA) increase that went into effect on December 1, 2025.
Additional monthly allowances can be added to this base rate if:
- The veteran was rated totally disabled (100% P&T or TDIU) for at least eight continuous years prior to death (adding an 8-year provision of $360.85 per month).
- The surviving spouse has dependent children.
- The surviving spouse requires Aid and Attendance (adding $421.00 per month due to disability or regular need for personal care).
Unlike some survivor benefits, DIC is not means-tested. Your personal income, employment status, and net worth have zero impact on your eligibility or the amount you receive.
Survivors Pension and Net Worth Limits
For surviving spouses of wartime veterans whose deaths were not service-connected, the VA offers a needs-based program called the Survivors Pension. Because this benefit is designed to assist low-income families, it is subject to strict financial limits.
For 2026, the net worth limit to qualify for the Survivors Pension is $163,699. The VA calculates net worth by combining your annual income with your personal assets (excluding your primary home and vehicle). The program pays the difference between your countable income and the Maximum Annual Pension Rate (MAPR) set by Congress:
- Surviving Spouse with no dependents: MAPR of $11,699 per year.
- Surviving Spouse qualifying for Aid and Attendance: MAPR of up to $18,697 per year.
If you are caring for an aging or ill family member and need to explore long-term care housing options, please read our VA Spouse Assisted Living Complete Guide to see how the Aid and Attendance allowance can offset these substantial costs.
How Remarriage Affects Survivor Benefits
A common question we receive is how remarriage impacts these hard-earned benefits. The rules depend entirely on the specific benefit and the age at which you remarry:
- DIC: If you remarry before age 57, your monthly DIC payments will stop. However, if that subsequent marriage ends due to divorce or death, your DIC eligibility can be restored. If you remarry on or after age 57, you will continue to receive your monthly DIC payments in full.
- CHAMPVA: If you remarry before age 55, your health coverage terminates. If you remarry on or after age 55, you retain your CHAMPVA benefits.
- DEA (Chapter 35): Educational benefits are generally not affected by remarriage, allowing you to continue your studies.
For a comprehensive checklist of how life changes impact your survivor status, review the official VA Benefits For Family And Caregivers portal.
Caregiver Support and VA Home Loans for Special Operations Families
The physical toll of being a Navy SEAL is immense. Years of heavy carries, parachute jumps, combat diving, and repeated exposure to blast overpressure can lead to severe physical disabilities, traumatic brain injuries (TBI), and post-traumatic stress disorder (PTSD). Often, the spouse quietly transitions into the role of a full-time caregiver.
To understand how the VA rates these complex, multi-system injuries, consult our VA Disability Rating Charts Ultimate Guide.
Program of Comprehensive Assistance for Family Caregivers (PCAFC)
If you are providing daily, in-person personal care services to a disabled Navy SEAL veteran, you may qualify for the Program of Comprehensive Assistance for Family Caregivers (PCAFC). This program provides designated primary family caregivers with:
- A monthly financial stipend (calculated based on the geographic cost of living and the level of care required).
- Access to health insurance through CHAMPVA (if the caregiver doesn't already have health coverage).
- Mental health counseling and specialized caregiver training.
- Up to 30 days of respite care per year to prevent caregiver burnout.
The program categorizes care into two tiers:
- Level 1 (Substantial Caregiving): For veterans who require significant assistance but do not require continuous supervision.
- Level 2 (Continuous Supervision): For veterans with severe cognitive or physical impairments who require constant, round-the-clock supervision and assistance with three or more activities of daily living.
Navigating the application process can be challenging. According to a report by the VA Office of Inspector General (OIG), the VA caregiver program previously paid out $8 million to caregivers of veterans who did not meet the strict eligibility criteria, leading to highly rigorous reassessments for all applicants.
However, the program has expanded significantly. Approximately 20,000 veterans were enrolled before the program was expanded to include veterans of all eras, adding an estimated 41,000 or more families to the system. If you need assistance gathering evidence to support your caregiver application, read our guide on filing VA Disability Claims.
VA Home Loan Eligibility for Surviving Spouses
The VA home loan benefit is one of the most powerful wealth-building tools available to military families. It allows you to purchase a home with zero down payment, no monthly private mortgage insurance (PMI), and highly competitive interest rates.
Surviving spouses can utilize this benefit to buy, build, or refinance a home if they obtain a Certificate of Eligibility (COE). To qualify, you must be:
- The unremarried surviving spouse of a service member who died in the line of duty or from a service-connected cause.
- A surviving spouse who remarried after age 57 (on or after December 16, 2003).
- The spouse of a service member who is officially listed as MIA (Missing in Action) or a POW (Prisoner of War).
Additionally, qualifying surviving spouses are completely exempt from paying the standard VA funding fee, saving thousands of dollars in closing costs.
Navy SEAL Foundation (NSF) and Special Operations Resources
Because federal VA benefits can sometimes take months to process, private organizations step in to bridge the gap. The Navy SEAL Foundation (NSF) is a premier non-profit organization dedicated specifically to the Naval Special Warfare community.
The NSF dedicates 15% of its total annual programs budget (an estimated $3 million) to support Gold Star and Surviving Families through wellness retreats, immediate tragedy assistance, counseling, and educational scholarships.
Furthermore, the NSF actively funds cutting-edge clinical trials to treat the unique cognitive injuries of special operators. This includes a landmark $50,000 investment in MAPS's MDMA-assisted therapy research in 2020 to address treatment-resistant PTSD.
For direct access to emergency grants, legal aid, and wellness support, visit the Resources For Veterans & Warriors page.
Understanding the deep bonds and trials of special operations families is essential. If you want to explore the realities of maintaining a healthy home life under these conditions, we invite you to read our articles on Navy SEAL Marriages and the 10 Shocking Navy SEAL Husband Qualities You Dont Know.
Frequently Asked Questions about Navy SEAL Spouse Benefits
Can a Navy SEAL spouse receive both DIC and SBP?
Yes. Historically, there was a dollar-for-dollar offset known as the "Widows Tax," which forced surviving spouses to give up their military Survivor Benefit Plan (SBP) payments if they received DIC.
Fortunately, Congress fully eliminated this offset. Surviving spouses who qualify for both programs now receive both their monthly DIC payments and their SBP payments in full, ensuring much greater financial stability.
What happens to CHAMPVA eligibility if a surviving spouse remarries?
If you remarry before the age of 55, your CHAMPVA healthcare benefits will terminate on the date of your remarriage. However, if that marriage later ends due to divorce, annulment, or death, you can apply to have your CHAMPVA benefits fully restored. If you remarry after age 55, your coverage remains uninterrupted.
How do Navy SEAL spouses apply for a VA home loan Certificate of Eligibility (COE)?
To apply for a COE as a surviving spouse, you must submit VA Form 26-1817 (Request for Determination of Loan Guaranty Eligibility - Unmarried Surviving Spouses) to the VA, along with the veteran's DD-214 and death certificate. You can submit these documents online through VA.gov or work directly with a VA-approved lender to pull the certificate automatically.
Conclusion
Navigating VA military benefits for Navy SEAL spouses requires patience, precision, and proactive planning. Whether you are transitioning from active duty, managing a severe disability, or rebuilding your life after a loss, these benefits represent a sacred promise earned through your family's profound sacrifices.
As you prepare for the next chapter, remember to utilize time-sensitive resources. Transitioning families should review the official guide on Service Members Separating Or Retiring From Service to avoid missing critical enrollment deadlines.
At USMilitary.com, we are committed to being your trusted guide through every step of this journey. We invite you to Explore All About U.S. Veteran Benefits to discover more tools, rates, and step-by-step guides tailored for your family. For more inspiration on overcoming the unique obstacles of military life, check out the powerful lessons in Dare to Live Greatly.