What Every Navy Veteran Needs to Know About VA Home Loan Appraisal Requirements
VA home loan appraisal requirements exist to protect you — the veteran — from overpaying for a property or buying a home with serious safety problems. Before the VA will guarantee your loan, a licensed VA fee appraiser must confirm two things: the home's fair market value, and that it meets the VA's Minimum Property Requirements (MPRs).
Here's a quick snapshot of what the VA appraisal process covers:
| What the VA Appraisal Does | What It Does NOT Do |
|---|---|
| Establishes fair market value | Replace a home inspection |
| Checks for safety, sanitation, and structural soundness | Catch hidden or latent defects |
| Confirms the home meets VA MPRs | Perform operational checks on appliances |
| Results in a Notice of Value (NOV) valid for 6 months | Guarantee the home is a good deal |
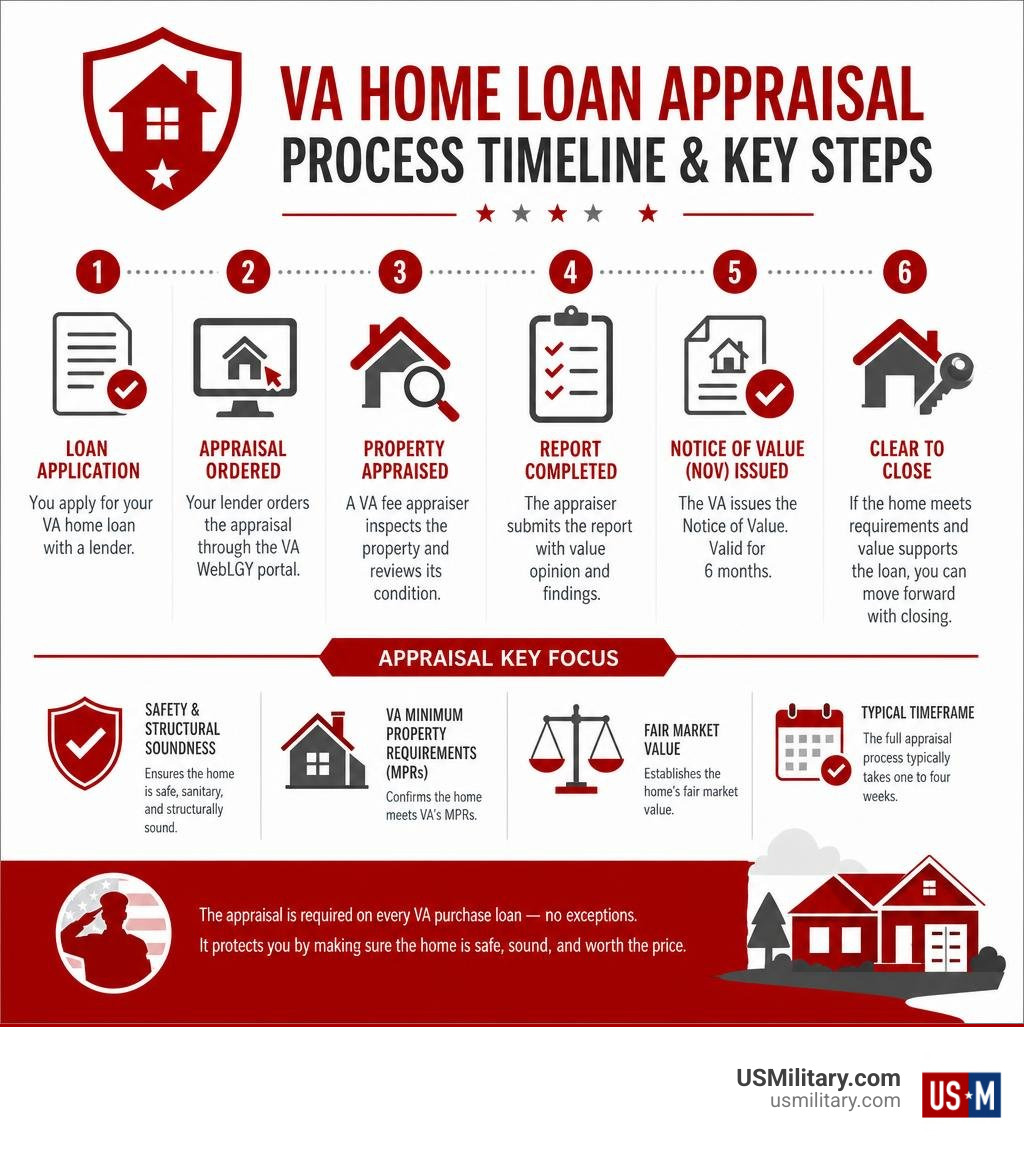
The appraisal is required on every VA purchase loan — no exceptions. It's ordered by your lender but assigned independently by the VA through its WebLGY portal. The full process typically takes one to four weeks.
If the appraised value comes in below the purchase price, or the property needs repairs to meet MPRs, you have options — including renegotiating with the seller, requesting a Reconsideration of Value, or walking away with your earnest money intact under the VA Escape Clause.
Understanding this process before you make an offer can save you time, money, and stress.
I'm Larry Fowler, BUD/S class 89 graduate and publisher of the USMilitary.com Network since 2007 and a long-time resource on VA benefits — including VA home loan appraisal requirements — for active-duty service members and veterans. In this guide, I'll walk you through every step of the appraisal process so you can move forward with confidence.
What is a VA Loan Appraisal and How Does the Process Work?
When you purchase a home using your hard-earned benefits, the property itself acts as the collateral for your mortgage. Because of this, we must ensure the home is a safe investment for you and a secure asset for the lender. This is where the VA loan appraisal comes into play.
A VA appraisal is a comprehensive evaluation of the property. It serves a dual purpose:
- Property Valuation: It determines the fair market value of the home to ensure you are not borrowing more than the property is actually worth.
- Safety and Soundness Check: It verifies that the home meets the Department of Veterans Affairs' strict standards for safety, sanitation, and structural integrity.
To understand the core of these benefits, it helps to review the official VA Home Loan Definition. This specialized loan program is designed to provide favorable terms, but those terms depend on the property meeting the VA's standard of quality.
The appraiser compiles their findings, including comparable sales and property condition details, into a standardized report. This document is then uploaded to the VA's secure WebLGY portal, which serves as the central hub for the VA fee panel.
Who Orders and Assigns the Appraiser?
To keep the valuation objective and unbiased, neither you nor your seller can choose the appraiser. In fact, your lender cannot pick them either.
Once you are under contract and your loan application is underway, your lender will initiate the appraisal request. The VA then uses a randomized, independent rotation system to assign a certified appraiser from the official VA fee panel. These appraisers are not government employees; they are independent, credentialed professionals who are trained to enforce VA guidelines.
This strict separation ensures that the valuation remains completely objective. If there is an appraiser shortage or high demand in a specific market, the VA outlines specific protocols for alternative valuation methods, such as desktop or exterior-only appraisals, under the guidelines established in the Procedures for Alternative Valuation Methods.
The Timeline of a VA Appraisal
While the actual on-site evaluation of the home is relatively brief — usually taking just a few hours — the entire administrative process typically takes between one to four weeks.
Here is how the timeline generally unfolds:
- Scheduling (1 to 2 Business Days): Once assigned, the appraiser is expected to make contact to schedule the property visit within two business days.
- The On-Site Visit: The appraiser conducts the physical walkthrough, taking photos and checking major systems.
- Report Preparation and Upload (10 Business Days on Average): The appraiser analyzes local market data, finds comparable sales, and uploads the completed report to the VA portal.
- Staff Appraisal Reviewer (SAR) Review (5 Business Days): Once the report is uploaded, the lender's SAR reviews the document to ensure compliance and officially issues the Notice of Value (NOV).
Understanding VA Home Loan Appraisal Requirements and MPRs
To qualify for VA financing, a home must meet the VA's Minimum Property Requirements (MPRs). These are not designed to point out cosmetic flaws or minor wear and tear; instead, they focus entirely on the safety, sanitation, and structural soundness of the property.
The official guidelines are detailed in the Chapter 12 Minimum Property Requirement manual. If a home fails to meet any of these basic criteria, the appraiser will note the deficiencies, and the issues must be resolved before your loan can close.
Core Minimum Property Requirements for VA Home Loan Appraisal Requirements
To give you a clear idea of what the appraiser looks for, here are the core areas evaluated under the VA home loan appraisal requirements:
- Heating and Electrical Systems: The home must have a safe, functioning heating system capable of maintaining a comfortable temperature. Mechanical and electrical systems must be in good working order, free of hazards like exposed wiring.
- Clean Water and Sanitation: The property must have a reliable, continuous supply of safe drinking water and a safe method of sewage disposal. If the home uses an individual well, the water must be tested by a third party, and the results are valid for 90 days.
- Roofing Life: The roof must be in good condition and prevent moisture from entering the home. The VA generally requires that the roof has a remaining useful life of at least two years.
- Lead-Based Paint: For homes built before 1978, any peeling, chipping, or cracking paint must be scraped, primed, and repainted to prevent lead poisoning hazards.
- Pest Control: The property must be free of active wood-destroying insect infestations (like termites). In many regions, a separate termite inspection report is required.
- Structural Soundness: The foundation, crawl spaces, attics, and basements must be dry, properly ventilated, and structurally sound.
Sellers should be aware of these standards before listing their properties. If you want to know how this affects the seller's side of the transaction, read our guide on VA Loan Requirements for Sellers.
Special Property Considerations for VA Home Loan Appraisal Requirements
Different types of properties have unique guidelines under the VA program:
- New Construction: For homes currently being built or recently completed, the builder must have a valid VA Builder ID. Additionally, special inspections and warranties may be required to protect your investment. You can find more detailed builder and registration resources through the official Construction and Valuation - VA Home Loans portal.
- Flood Zones: If the home is located in a FEMA-designated Special Flood Hazard Area (SFHA), you must obtain flood insurance to secure the loan. Properties located in active lava flow zones or coastal barrier resource systems are generally ineligible.
- Manufactured and Mobile Homes: Yes, you can use a VA loan to buy a manufactured home, but it must be classified as real estate, sit on a permanent foundation, and meet specific structural guidelines. Check out the details in our guide on the VA Loan for Mobile Home.
- Buying Land: While the VA allows you to build a home, buying raw land with no immediate plans for construction is not permitted. Learn more about the specifics of land acquisition in our article Can You Buy Land with a VA Loan?.
VA Appraisal vs. Home Inspection: Key Differences
One of the most common mistakes homebuyers make is assuming that a VA appraisal is the same thing as a home inspection. It is not!
While both involve a professional looking at the home, their goals, depth, and responsibilities are entirely different. We always strongly recommend that you pay for an independent home inspection in addition to the required VA appraisal.
| Feature | VA Appraisal | Home Inspection |
|---|---|---|
| Is It Mandatory? | Yes, required for all VA purchase loans. | No, completely optional (but highly recommended). |
| Who Does It Protect? | Protects the lender and the VA (and gives you basic safety assurances). | Protects you, the buyer, by revealing hidden issues. |
| What Is the Focus? | Fair market value and basic MPR compliance. | Detailed physical condition of all systems and structural elements. |
| How Deep Does It Go? | Visual inspection of major areas and systems. | In-depth testing of outlets, plumbing, appliances, and structural integrity. |
| Who Pays? | The buyer pays (as part of closing costs). | The buyer pays directly to the inspector. |
To make sure you meet all the personal eligibility criteria before focusing on the property, review the VA Home Loan Qualifications. Understanding how these rules compare to other financing options can also help you decide if this is the right path; you can compare the options in our breakdown of the Pros and Cons of VA Loan vs Conventional Loan.
VA Appraisal Fees, Timeliness, and the Notice of Value (NOV)
VA appraisal fees and timeliness requirements are strictly regulated to protect veterans from price gouging. These fees vary by region and are updated periodically. For example, VA appraisal fees in the Northwest might run around $1,000, while the cost in the Midwest and the South is typically closer to $700 to $900.
The VA implemented updated rules for appraisals ordered on or after May 1, 2026. These standards establish clear guidelines for fees and timelines:
- No Extra Liquidation Fees: Appraisers are no longer authorized to charge an additional $50 above the posted fee schedule for liquidation appraisals.
- 30-Day Payment Window: Payments to the appraiser must be made within 30 days of billing. Late fees are authorized if payment is delayed beyond this window.
- Standardized Cancellation Schedule: If an assignment is cancelled, the appraiser is paid based on a specific tier of completed work:
- Work completed after acceptance but prior to setting an appointment: Maximum of $50.
- Appointment scheduled and confirmed prior to cancellation: Maximum of $175.
- Interior review of the property is completed: Maximum of 50% of the posted fee.
- Report fully completed, signed, and uploaded: Full fee is paid.
Lenders can review the exact, up-to-date state-by-state schedules on the VA Appraisal Fee Schedules and Timeliness Requirements page.
What is the Notice of Value (NOV)?
Once the appraiser completes the report, the lender’s Staff Appraisal Reviewer (SAR) evaluates it and issues the Notice of Value (NOV). This is the official document that establishes the "reasonable value" of the home for the loan guarantee.
The NOV is valid for six months from the date of the appraisal. If your loan does not close within this six-month window, you may need to order a new appraisal. The NOV will also list any specific conditions or repairs that must be completed before the loan can be finalized.
For a deeper dive into how these valuations are reviewed and managed, you can read the regulatory details in Chapter 11: Appraisal Requirements - ACES IQ Reference Materials and Microsoft Word - Ch10AppraisalProcess_NEW.
What Happens If the Appraisal Comes in Low or Repairs Are Needed?
If the appraisal matches or exceeds your purchase price and the home meets all MPRs, you are in the clear! However, if the appraisal comes in low or the appraiser notes required repairs, your transaction hits a temporary speed bump.
Before making an offer, it is smart to calculate your budget. Our How Much House Can I Afford VA Loan? guide can help you establish a safe price range.
If the appraisal reveals that repairs are needed, the seller is typically asked to fix the issues before closing. If the seller refuses, you can negotiate to pay for the repairs yourself, request an MPR waiver from the VA on a case-by-case basis, or utilize your contract protections to walk away.
The Tidewater Initiative and Reconsideration of Value (ROV)
If the appraiser believes the home's value is going to come in below the agreed-upon purchase price, they do not just upload a low value. Instead, they must initiate the Tidewater Initiative.
This process gives your real estate agent and lender two business days to submit additional comparable sales (comps) to support the purchase price. If the appraiser reviews the new data and still cannot justify the purchase price, they will complete the report with the lower value.
If Tidewater does not resolve the issue, you can request a formal Reconsideration of Value (ROV). This is a formal appeal where the lender's SAR or the VA reviews the valuation. An ROV typically takes 5 to 10 business days to process. You can read more about how lenders handle these unique challenges in the guide An In-Depth Look at the VA Appraisal - Veterans United Home Loans.
The VA Escape Clause Protection
What happens if the appraisal comes in low, and you cannot reach an agreement with the seller to lower the price?
Thanks to federal law, you are protected by the VA Escape Clause (also known as the VA Amendment to Contract). This clause must be included in every VA purchase contract. It states that you cannot be forced to complete the purchase or lose your earnest money deposit if the property's appraised value is lower than the contracted purchase price.
This is an incredibly powerful consumer protection that ensures you are never financially penalized for a low appraisal. You can find more details on how the VA protects buyers and manages appraiser panels on the official VA Home Loans - Appraisers/Staff Appraisal Reviewer resource page.
Frequently Asked Questions about VA Appraisals
Can I choose my own VA appraiser?
No. To maintain complete impartiality, the VA uses a strict rotation system to assign appraisers through its WebLGY portal. Neither the buyer, the seller, nor the lender can select or influence who conducts the appraisal.
Does a VA appraisal guarantee the home is free of defects?
No. The VA appraisal only checks that the home meets Minimum Property Requirements for basic safety and structural soundness. It is not a substitute for a comprehensive home inspection, which examines systems, appliances, and hidden issues in much greater detail.
Who pays for the VA appraisal fee?
The homebuyer is responsible for paying the appraisal fee upfront, though it is considered a closing cost. You can negotiate with the seller to have them credit you for this cost at closing, but the buyer must initially cover the fee.
Conclusion
Navigating the VA home loan appraisal requirements can seem daunting, but these rules are designed with your best interests in mind. They ensure you move into a home that is safe, structurally sound, and worth the price you agreed to pay. By working with a VA-savvy real estate agent and lender, you can easily navigate the timeline, handle potential repair requirements, and use your hard-earned benefits to achieve the American dream of homeownership.
At USMilitary.com, we are dedicated to providing the most comprehensive, up-to-date resources for our service members, veterans, and military families. Whether you are exploring home loan benefits, retirement planning, or career paths, we are here to support you at every stage of your journey.
Ready to take the next step toward owning your home? Explore VA Home Loan Benefits on USMilitary.com today!