
What Are Department of Veterans Affairs Home Loans?
Department of Veterans Affairs home loans are a mortgage benefit earned through military service — and one of the most powerful financial tools available to veterans, service members, and eligible surviving spouses.
Here's a quick overview of what you need to know:
| Feature | Details |
|---|---|
| What it is | A home loan backed (guaranteed) by the VA, issued by private lenders |
| Who qualifies | Veterans, active-duty service members, National Guard, Reserve members, and eligible surviving spouses |
| Down payment | $0 required in most cases |
| Private mortgage insurance | Not required |
| Loan types | Purchase, cash-out refinance, IRRRL, NADL, renovation, and more |
| How to start | Obtain a Certificate of Eligibility (COE) through VA.gov or your lender |
| Lifetime benefit | Yes — can be used multiple times |
The VA doesn't actually lend you the money. Instead, it guarantees a portion of the loan, which allows private lenders to offer better terms — like no down payment and no private mortgage insurance (PMI). Since 1944, the VA has guaranteed more than 28.5 million loans, helping generations of military families buy homes.
Whether you're buying your first home, refinancing, or exploring your options for the first time, understanding how this benefit works can save you thousands of dollars.
I'm Larry Fowler, publisher of the USMilitary.com Network since 2007 and a longtime advocate for veteran financial benefits, including Department of Veterans Affairs home loans. I've spent nearly two decades helping veterans cut through confusing government programs to find the benefits they've earned. Let's break this down simply, so you know exactly where you stand.
Understanding Department of Veterans Affairs Home Loans

When we talk about department of veterans affairs home loans, the most important concept to wrap your head around is the "VA guaranty."
Because the VA guarantees up to 25% of the loan amount to private lenders in the event of a default, lenders feel incredibly secure. This federal backing is what allows us to secure historically low interest rates and completely bypass the down payment requirement. You can read the full legislative history and structure of these programs in the official congressional report on VA Home Loan Programs.
Over the years, we have seen this program adapt to protect military families during tough times. For instance, the VA offers robust foreclosure avoidance and loss mitigation resources. In 2025, the VA even established a partial claim program to assist veterans who fell behind on their mortgages, ensuring that keeping veterans in their homes remains a top priority. It is no wonder that MBA foreclosure data shows VA loans have been the safest loan option on the market for most of the last 18 years.
Types of Department of Veterans Affairs Home Loans Available
Your military home loan benefit is not a one-size-fits-all program. Depending on your goals, we can choose from several different loan types:
- VA Purchase Loans: The classic route. You can buy an existing single-family home, a VA-approved condo, a manufactured home, or even build a new home from scratch. In FY2025, purchase loans saw an 8.5% increase, rising to 323,835 loans compared to 298,327 in FY2024.
- Interest Rate Reduction Refinance Loan (IRRRL): Also known as a "streamline refinance." If you already have a VA loan, this program allows you to roll into a lower interest rate with minimal paperwork and often no appraisal. Thanks to changing market dynamics, IRRRL volume surged by 135% in FY2025, jumping from 50,826 to 119,459 loans. If you are wondering whether this makes sense for you, check out our guide on Can You Refinance a VA Loan.
- Cash-Out Refinance: This option allows you to replace your current mortgage (VA or non-VA) with a new VA loan while pulling cash out of your home’s equity to pay off debt or make improvements. Cash-out refinances grew 26.5% year-over-year in FY2025, reaching 85,049 loans.
- Native American Direct Loan (NADL): Unlike standard VA-backed loans, the NADL is a direct loan from the government. It helps Native American veterans buy, build, or improve homes on Federal trust land.
- VA Renovation Loans: These let you finance both the purchase of a home and the costs to repair or improve it into a single mortgage.
- Temporary Buydowns: If you want a lower payment during the first few years of your mortgage, you can use a temporary buydown. Funded by the seller, builder, or even yourself, these funds are held in escrow to reduce your interest rate temporarily (by up to 1% annually for up to three years). Learn more about the rules on VA Home Loans.
- Assumptions: Did you know that a VA loan can actually be transferred to a new buyer? To see how this works, read our article Can a VA Loan Be Assumed by a Non-Veteran.
How to Apply for Department of Veterans Affairs Home Loans
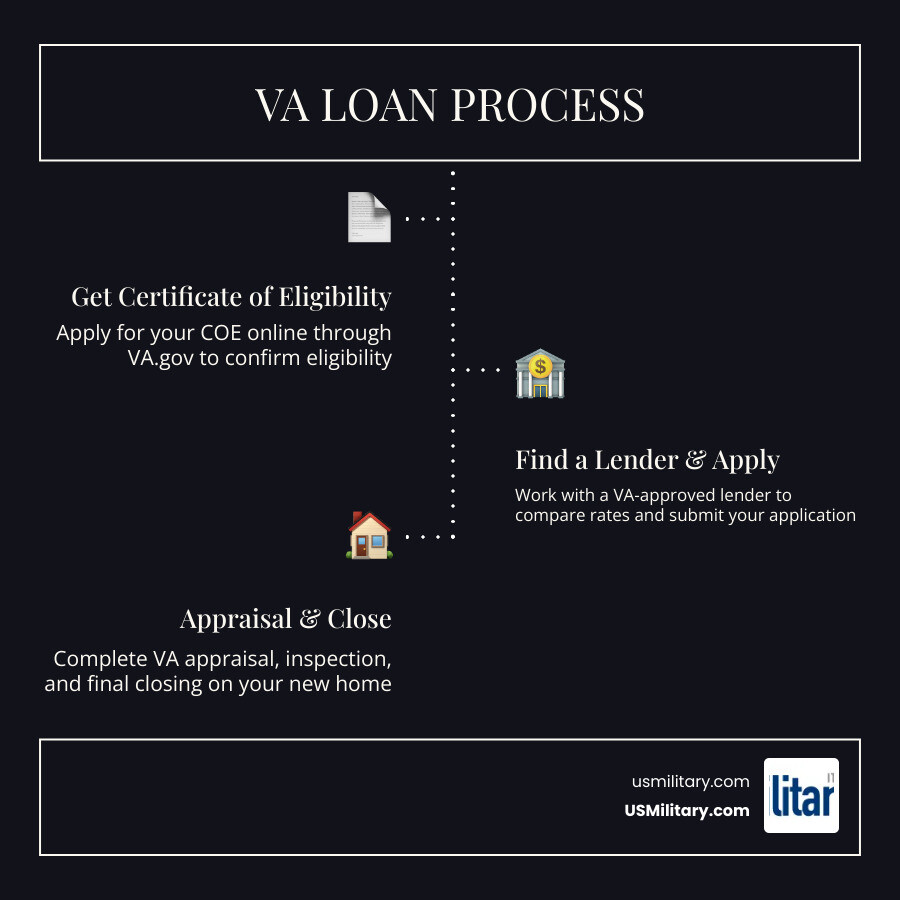
Getting started is simpler than you might think. We can break down the application process into a few clear steps:
- Obtain your Certificate of Eligibility (COE): This is the golden ticket that proves to a lender you meet the service requirements. You can apply for this online or ask your lender to fetch it for you.
- Review your finances: Lenders will check your credit profile, stable income, and debt-to-income (DTI) ratio. While the VA doesn't enforce a strict DTI limit, underwriters look closely at files exceeding 41% DTI to ensure you have enough residual monthly income to live comfortably.
- Shop lenders: Not all VA lenders are the same. We recommend checking out the Top VA Home Mortgage Lenders or reviewing our breakdowns on Leading VA Loan Lenders, Best Lenders for VA Home Loans, and the Best 10 VA Home Loan Lenders. You can even compare specific options like the USAA VA Home Loan to find your best fit.
- Include the VA Escape Clause: When you sign a purchase agreement, this clause guarantees you can walk away with your earnest money intact if the home doesn't appraise for the agreed-upon purchase price.
- Appraisal and Inspection: A VA-approved appraiser will evaluate the property to ensure it meets the VA's Minimum Property Requirements (MPRs) for safety and structural integrity. That a VA appraisal is not a substitute for a thorough home inspection!
For a detailed step-by-step walkthrough, check out the official guide on Buying A Home With A VA-Backed Loan | Veterans Affairs.
Eligibility and Service Requirements for VA Loans
Before we start house hunting, we must establish your eligibility. To qualify for department of veterans affairs home loans, you must meet minimum active-duty service requirements based on when and how you served.
For an extensive look at current rules, check out the 2026 VA Home Loan Requirements or review the official Eligibility - VA Home Loans guidelines.
Minimum Service Requirements and Exceptions
Service requirements differ depending on whether your service took place during wartime or peacetime:
- Wartime Service: Typically requires at least 90 continuous days of active duty.
- Peacetime Service: Typically requires at least 181 continuous days of active duty.
- Post-1980 (Enlisted) or Post-1981 (Officer): Usually requires 24 continuous months of service, or the full period for which you were called to active duty (but not less than 90 days in wartime or 181 days in peacetime).
- National Guard and Reserve: Historically required 6 creditable years. However, eligibility now extends to National Guard members with at least 90 days of active service, including at least 30 consecutive days under Title 32.
If you do not meet these minimum service requirements, you may still be eligible if you were discharged due to a service-connected disability, a medical condition, or a reduction in force.
Your discharge must be "other than dishonorable." If you received an unfavorable discharge, you can apply for a discharge upgrade or request a VA Character of Discharge review to see if your benefits can be restored.
Restoring Entitlement and Special Cases
One of the biggest myths we encounter is that you can only use a VA loan once. That is completely false! This is a lifetime benefit.
If you sell your home and pay off your VA loan in full, you can completely restore your entitlement to use again on another purchase. Under certain circumstances, you can even have two VA loans active at the same time using your remaining "partial entitlement." For a complete breakdown of how this works, read How Many Times Can You Use a VA Loan.
Special eligibility is also extended to surviving spouses. If you are an un-remarried spouse of a veteran who died in service or from a service-connected disability, you may be eligible to secure a COE and buy a home with the same incredible benefits.
Key Benefits of VA Loans vs. FHA and Conventional Mortgages
When we compare VA loans to conventional or FHA mortgages, the advantages are staggering.
First and foremost is the $0 down payment benefit. In FY2024, 74% of VA purchase borrowers made no down payment. On a conventional loan, making a down payment of less than 20% forces you to pay Private Mortgage Insurance (PMI) every month. With a VA loan, there is no monthly PMI, saving you hundreds of dollars on your monthly mortgage payment.
To see how these programs stack up side-by-side, we can look at this comparison table:
| Feature | VA Loan | FHA Loan | Conventional Loan |
|---|---|---|---|
| Typical Down Payment | 0% | 3.5% | 3% to 20% |
| Monthly Mortgage Insurance | None | Required (MIP) | Required if <20% down |
| Credit Flexibility | High (No official min) | Moderate | Strict |
| Average Origination Cost | Lowest | High | Moderate |
For a deeper dive into these options, read our comparison on VA Loan vs FHA vs Conventional.
VA Guaranty vs. FHA Mortgage Insurance
While FHA loans require an upfront and monthly Mortgage Insurance Premium (MIP), the VA loan program relies on the federal guaranty.
According to 2024 Home Mortgage Disclosure Act (HMDA) data, VA loans had the lowest median origination costs on the market. In fact, median FHA origination charges were 204% higher than VA charges, representing a massive difference of over $2,000 out of pocket. Conventional origination charges were also 91.53% higher than VA charges.
Combined with the lowest average interest rates in the industry, the VA loan is arguably the most powerful mortgage product ever created.
VA Loan Costs: The Funding Fee, Closing Costs, and Limits
While department of veterans affairs home loans offer incredible savings, they are not entirely free of costs. We need to plan for the VA funding fee and standard closing costs. To estimate your potential monthly costs, you can use our VA Loan Payment Calculator or explore the All About Top 7 Trusted VA Home Loan Calculators to find the right tool for your budget.
Understanding the VA Funding Fee and Exemptions
The VA funding fee is a one-time governmental fee that helps keep the loan program running for future generations. The fee is a percentage of your total loan amount and varies based on your down payment and whether it is your first or subsequent use:
- First-Time Use ($0 Down): 2.15% of the loan amount.
- Subsequent Use ($0 Down): 3.3% of the loan amount.
- IRRRL Streamline Refinance: 0.5% of the loan amount.
You can choose to pay this fee upfront at closing or roll it directly into your monthly mortgage payments.
Who is exempt? You do not have to pay the funding fee if you receive VA compensation for a service-connected disability (even a rating of 10% or higher), or if you are an eligible surviving spouse. To learn more about these special rules, read our guide on the 100 Percent Disabled Veteran Home Loan.
VA Loan Limits and Conforming Limits
If you have your full VA loan entitlement, there is no maximum limit on how much you can borrow with $0 down. The VA will guarantee 25% of your loan regardless of the price, though you still have to qualify based on your income and credit.
However, if you have active VA loans or have defaulted on a previous loan without restoring your entitlement, conforming loan limits (aligned with Fannie Mae and Freddie Mac limits) will apply to determine your maximum zero-down borrowing power. In high-cost counties, these limits are adjusted upward to help you buy in expensive markets.
Frequently Asked Questions about VA Home Loans
What is the minimum credit score for a VA loan?
The Department of Veterans Affairs does not set a minimum credit score requirement. However, private lenders will establish their own credit score minimums (known as "overlays"), which usually range between 580 and 620. This makes VA loans much more flexible and easier to qualify for than conventional mortgages.
Can you buy land or a mobile home with a VA loan?
Yes, you can! You can purchase a manufactured (mobile) home and a lot, or buy land to construct a home. To make sure you meet the proper guidelines, read our detailed guides on Can You Buy Land with a VA Loan and VA Loan for Mobile Home. That the property must meet the VA’s Minimum Property Requirements (MPRs) and be classified as real estate.
What happens if a borrower defaults on a VA loan?
If you fall on hard times, the VA has your back. They offer dedicated financial counseling and loss mitigation programs, such as repayment plans, loan modifications, and the partial claim program. If you are struggling, we recommend contacting a VA loan technician immediately to explore your options and protect your home.
Conclusion
Navigating homeownership can feel overwhelming, but your earned military benefits are designed to put the American dream within reach. Department of Veterans Affairs home loans offer unmatched savings, from $0 down payments to the lowest average interest rates on the market.
At USMilitary.com, we are committed to providing you with the resources, tools, and direct guidance you need to make informed financial decisions. If you are ready to take the next step on your homeownership journey, explore our comprehensive tools and Get Best VA Home Loan options today.
For more details on your lifetime benefits, read Your Guide to VA Home Loans from Service to Homeownership or start your journey directly by visiting our central hub for VA Home Loans on USMilitary.com.







