
What a VA Mortgage Loan Can Do for Navy SEALs
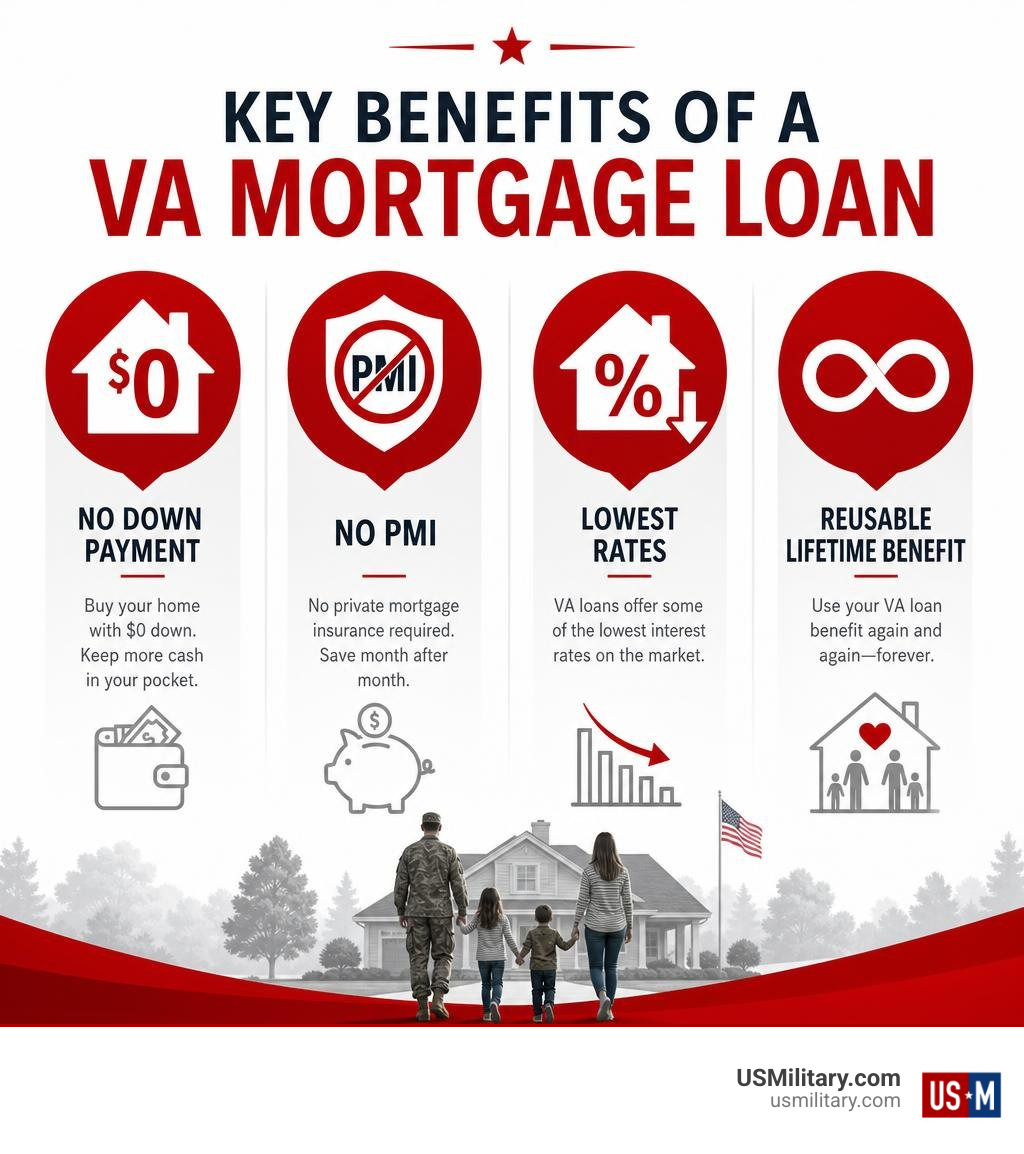
A VA mortgage loan is one of the most powerful home-buying benefits available to U.S. service members, veterans, and eligible surviving spouses. Here's a quick look at what makes it stand out:
| Feature | VA Loan | FHA Loan | Conventional Loan |
|---|---|---|---|
| Down payment | $0 required | 3.5% minimum | 3–20% typical |
| Private mortgage insurance (PMI) | None | Required | Required if <20% down |
| Origination costs | Lowest | 204% higher than VA | 91.53% higher than VA |
| Interest rates | Lowest on market | Higher | Higher |
| Foreclosure risk | Lowest (18 years running) | Higher | Higher |
| Reusable benefit | Yes, lifetime | No | No |
The VA has guaranteed more than 28.5 million loans since the program launched in 1944. In the 2025 fiscal year alone, veterans took out 323,835 VA purchase loans — up 8.5% from the year before.
These numbers tell a clear story: this benefit is being used, and for good reason.
I'm Larry Fowler, publisher of USMilitary.com and a longtime advocate for veterans navigating their VA benefits, including the VA mortgage loan program. Since 2007, I've helped hundreds of thousands of military members and veterans cut through the complexity of military financial benefits.
Below, we'll walk through every major VA mortgage loan option — from purchase loans and refinancing to specialized programs — so you can make a confident, informed decision.
Va mortgage loan terms to learn:
- Best VA Lender: New Day USA, Veteran United, Rocket Mortgage, Wholesale United, LoanDepot, or Navy Federal Credit Union
- New Day USA vs Veterans United Home Loan For My VA Home Loan
- The Best VA Home Lenders And Their Best Rates
What is a VA Mortgage Loan and How Does It Work?
At its core, a va mortgage loan is a home mortgage option backed by the federal government through the Department of Veterans Affairs. However, a common misconception is that the government directly lends you the cash.
In reality, the program works as a partnership. Private lenders—such as banks, credit unions, and mortgage companies—provide the actual funding for your home purchase or refinance. The VA provides a government guarantee on a portion of the loan, protecting the lender against total loss if you happen to default.
Because we have this government-backed safety net in place, lenders are willing to offer incredibly favorable terms. This unique structure is why we can enjoy benefits like zero down payments and highly competitive rates. You can explore our comprehensive breakdown of these programs on our VA Home Loans page, or read the official guidelines directly from the VA Home Loans - Veterans Benefits Administration.
Understanding the VA Mortgage Loan Guaranty
The magic behind the va mortgage loan lies in the VA guaranty. Typically, the VA guarantees 25% of the loan amount. This means if a borrower falls into foreclosure, the government reimburses the lender for up to a quarter of the loan value.
This security reduces the risk for lenders, allowing them to skip the standard requirement for private mortgage insurance (PMI) and drop their interest rates. It is a powerful safety net that has kept the veteran homeownership dream alive for over eight decades.
VA Loan vs FHA vs Conventional Mortgages
When we compare the primary mortgage options on the market, the advantages of the VA program become undeniable.
According to the most recent Home Mortgage Disclosure Act (HMDA) data, VA loans had the lowest median origination cost in 2024. To put that into perspective:
- Median conventional loan origination charges were 91.53% higher than VA charges.
- Median FHA loan origination charges were 204% higher than VA charges—a massive difference of $2,071.
Furthermore, Optimal Blue data consistently shows that VA loans carry the lowest average interest rates on the market.
Beyond cost, they are remarkably secure. Mortgage Bankers Association foreclosure data reveals that VA loans have been the safest loan type on the market for most of the last 18 years. This is largely due to the VA's robust underwriting standards and proactive foreclosure avoidance efforts.
To see how these programs match up head-to-head, read our in-depth comparison of the VA Loan vs FHA vs Conventional pathways.
Eligibility and Service Requirements for VA Home Loans
To take advantage of this lifetime benefit, you must meet specific service requirements established by the Department of Veterans Affairs. Eligibility is extended to active-duty service members, veterans, National Guard members, Reserve members, and certain surviving spouses.
To see if you qualify, you can review the complete VA Home Loan Eligibility Requirements or check out the official criteria outlined on the Eligibility For VA Home Loan Programs | Veterans Affairs portal.
Minimum Active-Duty Service Standards
Your eligibility depends heavily on when and how long you served. The general active-duty service standards are:
- Wartime Service: At least 90 continuous days of active duty.
- Peacetime Service: At least 181 continuous days of active duty.
- National Guard and Reserves: At least 6 creditable years of service. However, under modern regulations, National Guard members who have served at least 90 days of active service—including at least 30 consecutive days under Title 32 orders—are also eligible.
- Surviving Spouses: Un-remarried surviving spouses of service members who died in the line of duty or from a service-connected disability may qualify.
Note: If you were discharged due to a service-connected disability, hardship, or a reduction in force, you may still qualify even if you did not meet the standard service lengths.
How to Obtain Your Certificate of Eligibility (COE)
The very first step in the home-buying journey is proving your eligibility by obtaining a Certificate of Eligibility (COE). This document tells lenders that you have met the minimum service requirements to secure a VA-backed loan.
You can request your COE online through the VA.gov portal, have your lender retrieve it instantly through the WebLGY system, or apply by mail using VA Form 26-1880. To simplify this process, we have put together a step-by-step guide on How to Apply for a VA Home Loan.
Exploring Your VA Mortgage Loan Options
Whether you are looking to buy your very first home, build from the ground up, or refinance an existing mortgage to secure a lower rate, there is a va mortgage loan option designed to fit your goals. If you already have a mortgage, you might even ask, Can You Refinance a VA Loan to save money? The short answer is yes, and the options are highly flexible.
VA Purchase Loan Options
A VA purchase loan is the standard option for buying an existing home. It offers $0 down payment, no monthly mortgage insurance, and competitive interest rates.
When shopping for a home, we always recommend getting pre-approved by a lender first so you know your budget. To protect yourself, ensure your real estate agent includes the "VA Escape Clause" in your purchase agreement. This clause ensures that if the home appraises for less than the agreed purchase price, you can back out of the contract without losing your earnest money deposit.
To plan your journey, review the official steps on Buying A Home With A VA-Backed Loan | Veterans Affairs and use our financial tools to figure out How Much House Can I Afford with a VA Loan.
Refinancing with a VA Mortgage Loan
If you already own a home, refinancing can help you lower your monthly payments or pull cash out of your equity. As of July 2026, refinancing has surged in popularity due to shifting market rates. We generally utilize two primary refinance options:
- Interest Rate Reduction Refinance Loan (IRRRL): Often called a "Streamline Refinance," this option allows you to refinance an existing VA loan to a lower rate with minimal paperwork, no appraisal, and no income verification in most cases. IRRRL volume skyrocketed by 135% in the 2025 fiscal year, jumping from 50,826 to 119,459 loans as veterans rushed to secure lower rates.
- VA Cash-Out Refinance: This loan allows you to replace your current mortgage (VA or non-VA) and take out cash from your home's equity to pay off high-interest debt, fund home improvements, or cover emergency expenses. The VA will guarantee loans up to 100% of your home's value for a cash-out refinance. This option saw a 26.5% year-over-year increase in 2025, rising to 85,049 loans.
To explore these refinancing pathways further, visit our central hub for VA Home Loans.
Specialized VA Loan Programs
The VA also offers specialized programs designed for specific homeownership scenarios:
- Native American Direct Loan (NADL): Unlike standard VA-backed loans, the NADL is a direct loan program where the VA acts as the lender. It helps eligible Native American veterans buy, build, or improve homes on federal trust land.
- Adapted Housing Grants: For veterans with permanent and total service-connected disabilities, the VA offers grants (such as the Specially Adapted Housing grant) to help build an adapted home or modify an existing home to accommodate their needs. You can apply for these grants using VA Form 26-4555. Learn more about these life-changing resources on our Disabled Veteran Home Loan page.
VA Loan Costs, Fees, and Financial Guidelines
While a va mortgage loan offers incredible savings, it is not completely free of costs. Understanding the fees, closing costs, and underwriting requirements will help you plan your budget and avoid surprises at the closing table.
The VA Funding Fee Explained
Because VA loans do not require monthly mortgage insurance, the government charges a one-time administrative fee known as the VA Funding Fee. This fee helps sustain the loan program for future generations of veterans.
The fee is calculated as a percentage of your total loan amount and varies based on your down payment and whether it is your first time using the benefit:
- First-Time Use (Purchase/Cash-Out): 2.15% of the loan amount (with $0 down).
- Subsequent Use (Purchase/Cash-Out): 3.3% of the loan amount (with $0 down).
- IRRRL Refinance: 0.5% of the loan amount.
Note: You do not have to pay this fee out of pocket; you can roll it directly into your total loan amount. Additionally, you are entirely exempt from the funding fee if you receive VA disability compensation, are a Purple Heart recipient on active duty, or are an eligible surviving spouse.
Underwriting Standards and Residual Income
To protect veterans and lenders alike, the VA establishes clear underwriting standards under federal law, specifically outlined in 38 CFR 36.4340 | Underwriting standards, processing procedures, lender responsibility, and lender certification. | eCFR.io.
While the VA does not enforce a strict minimum credit score, individual lenders usually require a score of at least 620. Underwriters look at two primary metrics:
- Debt-to-Income (DTI) Ratio: The standard guideline is a DTI of 41% or less. However, you can exceed this limit if you have strong compensating factors, such as excellent credit or significant residual income.
- Residual Income: This is the amount of discretionary income you have left over each month after paying all major bills, taxes, and housing costs. The VA uses regional thresholds (Northeast, Midwest, South, West) based on your family size to ensure you have enough cash to comfortably cover daily living expenses like food and gas.
For a deep dive into these financial calculations, check out the VA Home Loan Guaranty Buyer’s Guide.
Rules on Occupancy, Reuse, and Foreclosure Prevention
The VA program is designed specifically to help veterans secure safe, stable housing for themselves and their immediate families. Because of this focus, there are strict rules regarding occupancy and how the benefit can be reused.
Reusing Your Benefit and Entitlement Restoration
One of the greatest myths about the VA loan is that it is a one-time deal. In truth, this is a lifetime, reusable benefit.
Your ability to reuse the benefit depends on your "entitlement"—the specific dollar amount the VA guarantees to your lender. If you have "full entitlement" (meaning you do not have an active VA loan), there are no limits on how much you can borrow without a down payment, provided you qualify financially.
If you have used your loan benefit before, you can restore your entitlement by:
- Selling the home and paying off the VA loan in full.
- Allowing another eligible veteran to assume your loan and substitute their entitlement for yours.
To learn how basic, bonus, and partial entitlements work in July 2026, read our complete guide: VA Loan Entitlement Explained. If you are selling a home, you may also want to explore how a VA Assumable Loan can make your property highly attractive to future buyers by letting them take over your existing lower interest rate.
What to Do If You Fall Behind on Payments
If you experience financial hardship, the VA offers some of the strongest foreclosure prevention assistance of any mortgage program.
The VA employs dedicated loan technicians who work directly with struggling borrowers and lenders to find viable alternatives to foreclosure. These solutions can include loan modifications, repayment plans, or temporary forbearance. If you are struggling, we urge you to contact a VA regional loan center at 877-827-3702 to explore your options.
Frequently Asked Questions about VA Loans
Do VA loans require a down payment or PMI?
No. In nearly 90% of cases, VA loans are secured with a $0 down payment. Additionally, because the federal government guarantees the loan, you are never required to pay private mortgage insurance (PMI), saving you hundreds of dollars every month compared to conventional or FHA loans.
Can you rent out a home purchased with a VA loan?
Yes, but with caveats. VA loans require you to occupy the property as your primary residence, usually moving in within 60 days of closing. However, once you have lived in the home for at least one year, you are generally free to rent it out. Additionally, you can buy a multi-unit property (up to four units) with a VA loan, live in one unit, and rent out the remaining units from day one.
Can you use a VA loan more than once?
Absolutely. The VA loan is a lifetime benefit. You can use it to buy a home, sell it, restore your entitlement, and buy another home. You can even have multiple active VA loans at the same time under certain "bonus entitlement" rules if you are relocating or upgrading your primary residence.
Conclusion
The va mortgage loan remains one of the most valuable benefits you have earned through your military service. With zero down payment requirements, no monthly mortgage insurance, and the lowest average interest rates on the market, it is an unmatched tool for building long-term wealth through homeownership.
At USMilitary.com, we are dedicated to helping our military community navigate these benefits with confidence. If you are ready to take the next step toward your homeownership dream, we invite you to explore the Best VA Loan Lenders and compare top-tier offers on our platform.
Ready to find the right partner for your mortgage journey? Visit Find the Best VA Home Loan Lenders today to get pre-approved, or return to our homepage at USMilitary.com for more military resources.







